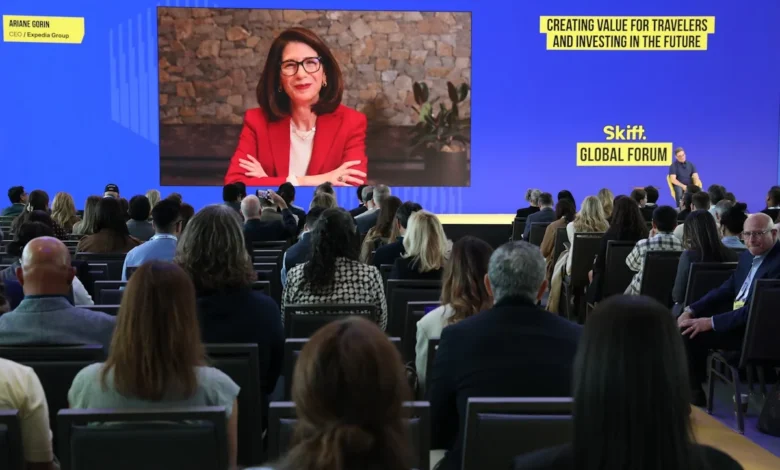
The rapid integration of generative artificial intelligence into consumer technology platforms has ushered in a period of strategic recalibration for the global travel industry, with online travel agencies (OTAs) closely evaluating how next-generation digital assistants will influence consumer behavior and impact bottom-line economics. Speaking during her recent corporate earnings call following the release of the company’s third-quarter financial results, Expedia Group CEO Ariane Gorin addressed the pressing question of how major artificial intelligence ecosystems—specifically Meta’s Muse and Google’s AI Overviews—will function as customer acquisition channels for industry leaders.
As technology giants continue to roll out advanced conversational interfaces and search-embedded generative summaries, travel conglomerates are actively navigating a shifting digital landscape. These platforms possess the capability to capture consumer intent at the earliest stages of trip planning, making them formidable intermediaries in the travel booking ecosystem. Gorin’s remarks shed light on the delicate negotiations and strategic frameworks currently defining the relationship between traditional OTAs and monolithic tech platforms, offering a glimpse into how customer acquisition costs and distribution dynamics are likely to evolve over the coming years.
The Intersection of Generative AI and Travel Distribution
For decades, the online travel agency business model has relied heavily on a predictable, albeit expensive, digital marketing playbook. Historically, customer acquisition has been driven by search engine optimization (SEO), paid search advertising, metasearch platforms, and targeted social media marketing. Companies like Expedia Group, Booking Holdings, and Airbnb allocate billions of dollars annually to secure visibility across dominant web gateways, most notably Google and social networks owned by Meta.
However, the advent of generative artificial intelligence threatens to disrupt this established funnel. Tools like Google’s AI Overviews and sophisticated generative models like Meta Muse are designed to provide direct, synthesized answers to complex user queries rather than merely serving up a list of blue links or traditional display advertisements. When a user asks an AI assistant to "plan a five-day family itinerary in Tokyo including boutique hotel recommendations and flights," the system generates a comprehensive response internally, potentially bypassing the traditional landing page experience that OTAs rely on to capture user data and secure bookings.
This paradigm shift forces companies like Expedia Group to adapt. Rather than viewing generative AI solely as a competitive threat that could disintermediate third-party sellers, industry leaders are exploring ways to integrate their vast inventories, pricing engines, and fulfillment capabilities directly into these new AI-driven ecosystems. Doing so requires establishing commercial agreements that define how travel products are displayed, who owns the customer relationship, and, crucially, what commission or advertising fees will be charged for traffic and transactions generated through AI platforms.
Financial Context and the Mechanics of Platform Partnerships
Addressing financial analysts and investors during the third-quarter earnings discussion, Gorin emphasized that the fundamental financial structures governing these emerging partnerships remain under active construction.
"The economics of the partnerships are being worked out," Gorin stated, pointing to the ongoing dialogue between travel providers and tech giants. Despite the uncertainties inherent in any nascent technological wave, Gorin expressed confidence in Expedia Group’s historical capacity to navigate platform shifts profitably.
"You know, we have a track record of being able to work with big advertising platforms or tech platforms to use them as channels to acquire customers at attractive economics, and that’s what I think we’ll see," she added.
This historical track record is rooted in decades of managing the ebbs and flows of digital marketing costs. Over the past twenty years, Expedia Group has adapted to the rise of mobile app stores, the dominance of algorithmic social media feeds, and continuous updates to search engine ranking criteria. In each instance, the company has had to balance the cost-per-click (CPC) or customer acquisition cost (CAC) against the lifetime value (LTV) of the traveler.
With generative AI platforms, the monetization models are still maturing. Tech platforms are currently experimenting with various formats, ranging from sponsored recommendations embedded within AI-generated text to API-driven booking modules that allow users to complete transactions without leaving the chat interface. For an OTA like Expedia, securing favorable terms in these emerging channels is vital to protecting profit margins in an increasingly competitive marketplace.
The Broader Industry Landscape: Competitors and Tech Giants
Expedia Group is not alone in assessing the impact of generative AI on customer acquisition. Across the travel sector, major players are racing to deploy proprietary AI tools while simultaneously negotiating access to external ecosystems.
Google’s rollout of AI Overviews has fundamentally transformed the search engine results page (SERP), capturing significant user attention before they even reach traditional travel aggregator sites. By synthesizing reviews, flight schedules, and hotel availability directly into the search interface, Google keeps users within its ecosystem longer. Similarly, Meta’s advancements in generative media and conversational agents position the social media giant to capture travel intent natively within platforms like Instagram, WhatsApp, and Facebook, where users frequently share vacation inspiration and seek peer recommendations.
Other industry competitors are adopting aggressive multi-pronged strategies. Booking Holdings, Expedia’s primary global rival, has similarly emphasized its investments in proprietary generative AI trip planners, such as its AI-powered assistant designed to facilitate conversational travel searches. However, executives across the industry universally acknowledge that proprietary tools alone cannot match the massive, daily user traffic commanded by platforms like Google and Meta. Consequently, establishing commercial pathways into these external AI engines is an operational necessity.
At the same time, regulatory scrutiny surrounding digital gatekeepers adds a layer of complexity to these partnerships. Antitrust regulators in the United States, the European Union, and other jurisdictions are closely monitoring how tech giants leverage their dominant search and social platforms to preference their own services or extract burdensome economic terms from third-party advertisers. As Expedia and other OTAs negotiate the economics of Meta Muse and Google AI Overviews, the shadow of regulatory oversight looms large, potentially influencing how revenue-sharing and data-access agreements are structured.
Strategic Implications for Expedia Group Moving Forward
As Expedia Group continues to execute its technological roadmap—which includes unifying its backend platforms across brands like Expedia, Hotels.com, and Vrbo—the integration of external AI channels represents a critical strategic vector.
The successful monetization of AI-driven acquisition channels depends on several key factors:
- Attribution and Data Transparency: OTAs must be able to accurately measure the return on investment (ROI) derived from AI-generated recommendations, ensuring that customer acquisition costs remain aligned with historical efficiency benchmarks.
- User Experience and Brand Loyalty: If AI assistants abstract the booking process entirely, OTAs risk becoming invisible fulfillment utilities behind the scenes. Maintaining direct consumer touchpoints and loyalty program engagement remains a core priority for executive leadership.
- Inventory Exclusivity and Dynamic Pricing: Ensuring that real-time pricing, availability, and loyalty perks are accurately reflected across third-party AI interfaces requires sophisticated technical integrations via robust APIs.
Gorin’s recent commentary suggests that while the financial terms of these arrangements are still being finalized, the foundational approach will be grounded in disciplined capital allocation and strategic collaboration. As consumer adoption of generative AI accelerates, the ability of online travel agencies to secure profitable placement within these new digital storefronts will play a decisive role in shaping the competitive hierarchy of the global travel industry for the remainder of the decade.