The Rising Cost of Inequality: Disproportionate Insurance Premiums Burden Black and Hispanic Homeowners Amid Climate Crisis

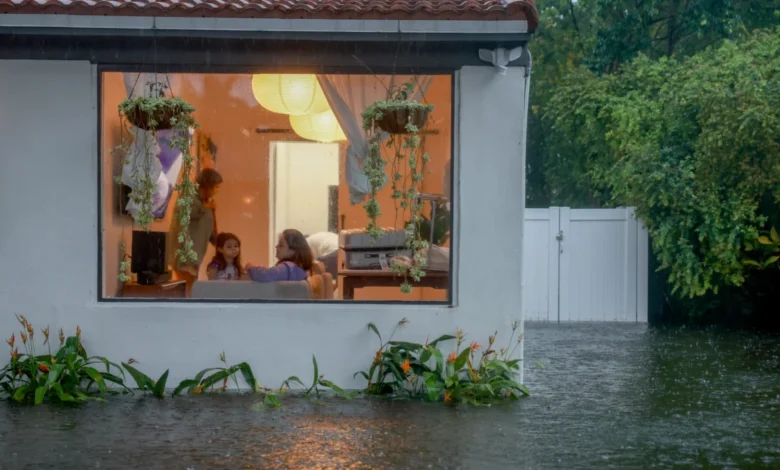
A troubling pattern of financial inequity is emerging within the United States housing market, where homeowners in predominantly Black and Hispanic communities are facing significantly higher insurance premiums than their counterparts in predominantly white neighborhoods. A comprehensive report published this July by the Consumer Federation of America (CFA), a coalition representing nearly 250 consumer advocacy groups, highlights that these systemic disparities persist even when controlling for property value, coverage limits, and individual homeowner characteristics. As the climate crisis accelerates the frequency of billion-dollar disasters—from catastrophic flooding in Florida to devastating wildfires in the West—the inability to afford adequate property insurance is increasingly positioning communities of color at a severe economic and physical disadvantage.
The Scope of the Disparity
The CFA’s investigation, which utilized an analysis of identical insurance policies to isolate potential bias, revealed stark figures. Homeowners residing in predominantly Hispanic zip codes are paying, on average, 30 percent more in annual premiums—amounting to an additional $950 per year—than residents in white-majority zip codes. The trend is similarly concerning for Black homeowners, who face an average premium hike of 16 percent, or $500 more annually, compared to their white counterparts.
When extrapolated over the lifespan of a standard 30-year mortgage, these costs represent a massive wealth transfer. For families in Hispanic communities, this translates to at least $28,500 in additional, non-recoverable insurance costs. For Black homeowners, the cumulative financial burden reaches approximately $15,000. These figures represent a significant barrier to wealth accumulation, particularly for households that rely on homeownership as their primary vehicle for building intergenerational equity.
A Historical Trajectory: From Redlining to Algorithmic Bias
To understand the current crisis, one must look at the historical context of housing in America. The practice of "redlining"—a mid-20th-century government-backed policy that designated minority neighborhoods as high-risk for mortgage lending—effectively barred Black and Hispanic families from purchasing homes in many desirable areas. While the Fair Housing Act of 1968 legally abolished these discriminatory practices, the damage to community development, public infrastructure, and property values remains etched into the American landscape.
Today, critics argue that the insurance industry is replicating these exclusionary patterns through modern, "inadvertent" means. In the 1990s, the industry faced significant legal scrutiny for overt discrimination. Major insurance providers, including Nationwide and American Family Mutual Insurance Company, were subject to multi-million dollar settlements after investigations revealed that agents were actively discouraged from soliciting business in Black neighborhoods, and that underwriters were using racial profiling to deny coverage or provide inferior, more expensive policies to minority applicants.

While industry spokespeople maintain that such overt discrimination is a relic of the past, the current landscape of "proxy" variables has replaced explicit racial designations. Modern underwriting models rely heavily on proprietary algorithms and artificial intelligence. These systems often integrate factors like credit scores—which themselves are influenced by decades of systemic inequality in banking and lending—as a proxy for risk. Research by the CFA has indicated that homeowners with lower credit scores pay an average annual penalty of nearly $2,000, or 99 percent more for coverage, effectively penalizing residents of lower-income and minority communities for the lingering effects of structural economic barriers.
Regional Case Studies in Financial Strain
The disparity is not uniform across the nation; rather, it is concentrated in specific geographic regions where the insurance market is already under immense pressure. Florida stands as the most acute example of this phenomenon. In predominantly Hispanic zip codes within the Sunshine State, homeowners face a staggering 58 percent higher premium rate compared to those in white communities, costing them upwards of $5,000 annually.
In the Northeast and Midwest, the trends are equally pronounced. Michigan leads the nation in disparities for Black homeowners, where premiums in predominantly Black zip codes are 74 percent higher than in white neighborhoods. Pennsylvania follows with a 57 percent gap. These figures are exacerbated by the broader national trend of rising insurance costs: between 2021 and 2024, the average cost of home insurance for all Americans climbed by 24 percent, a surge driven by the rising costs of climate-related disaster recovery.
Industry Defenses and Regulatory Stances
Representatives for the insurance industry strongly reject the notion that current rating practices are rooted in racial bias. Mark Friedlander, a spokesperson for the Insurance Information Institute, noted that the insurance sector operates under a strict, state-regulated framework that forbids the use of race or ethnicity in rate-setting.
"Using race, or any proxy for race, to set insurance rates is illegal in every US jurisdiction," Friedlander stated. "State insurance regulators review and approve the rating factors insurers use precisely to guard against that." According to the industry perspective, higher premiums in these communities are a direct reflection of "objectively higher catastrophe exposure" or higher costs associated with rebuilding older, lower-value housing stock.
However, advocates argue that this "risk-based" explanation fails to account for the lack of investment in infrastructure within these communities. As climate-related risks—such as urban heat islands and poor flood mitigation—disproportionately impact minority neighborhoods due to a historical lack of public investment, the insurance industry’s "risk-based" pricing essentially charges residents for the systemic neglect of their neighborhoods.

The Path Forward: Transparency and Resilience
The debate over insurance equity is arriving at a critical juncture as extreme weather events become the new norm. For policymakers, the challenge is to balance the actuarial realities of the insurance market with the mandate for fair housing.
Experts like Sharon Cornelissen of the Consumer Federation of America emphasize that bias often "creeps in" through the use of complex, opaque algorithms. "A lot of this could be through AI models or other factors that have a disproportionate impact on Black and Hispanic communities," she said, noting that without greater transparency into how these models weigh data, it is impossible for regulators to ensure true equality.
Proposals for reform are beginning to gain traction among housing advocates and policy experts. These include:
- Mandatory Transparency: Requiring insurers to disclose the variables used in their AI-driven underwriting models to ensure they do not inadvertently create a disparate impact based on race.
- Increased Public Investment: Shifting the focus from premium pricing to structural mitigation. As Friedlander suggested, reducing risk through modernized building codes and public-funded flood mitigation projects could lower premiums across the board.
- Strengthened Regulatory Oversight: State insurance commissioners are being urged to conduct more rigorous audits of rate filings, specifically looking for the "disparate impact" of factors that may correlate with race.
The broader implication of this study is clear: if the insurance industry continues to rely on models that reflect historical inequities, the dream of homeownership—and the ability to protect that home against an increasingly volatile climate—will remain out of reach for a growing segment of the American population. As Moira Birss of the Climate and Community Institute aptly summarized, the current situation regarding affordability and race is "unconscionable" in a nation that identifies homeownership as a fundamental pillar of economic stability. Without a concerted effort to address the mechanisms of bias within the insurance market, the divide between the protected and the vulnerable will only continue to widen.