PayRewards Can Turn A $10,000 Business Bill Into 40,000 Points—Even If The Vendor Doesn’t Accept Credit Cards

The Mechanism of B2B Payment Intermediation
The core utility of PayRewards lies in its role as a payment intermediary. For many small and medium-sized enterprises, the inability to pay vendors—such as suppliers, landlords, or service providers—via credit card represents a significant missed opportunity for liquidity management and rewards accumulation. Traditionally, these businesses rely on Automated Clearing House (ACH) transfers or wire transfers, which offer no point-earning potential.
PayRewards functions as an "on-ramp" for these transactions. A business pays the vendor through the PayRewards platform using a credit card; the platform then delivers the payment to the vendor via bank transfer or check. This process effectively converts non-card-eligible expenses into credit card spend, which can be critical for meeting the high minimum-spend requirements of premium business credit card sign-up bonuses.
Fee Structure and Point Acquisition Economics
The financial viability of using such a service hinges on the transaction fee structure. PayRewards implements a tiered system, separating the standard processing cost from an optional "points-earning" surcharge.
For a standard $10,000 business expense, the costs and rewards vary significantly based on the chosen tier:
- Standard Card Processing: At a 2.9% fee, a $10,000 transaction costs $290. This generates the credit card issuer’s standard rewards but no additional PayRewards points.
- Core Tier: At a 4.65% total fee ($465), a user earns 1 PayRewards point per dollar, totaling 10,000 additional points.
- Plus Tier: At a 6.15% total fee ($615), a user earns 2 PayRewards points per dollar, totaling 20,000 additional points.
When these figures are combined with the 20,000 points typically earned from a credit card offering 2 points per dollar, a business can accumulate 40,000 total points for a $615 investment. This results in an effective acquisition cost of approximately 1.54 cents per point, a figure that is frequently lower than the valuation of premium international cabin seats on partner airlines.
Market Context and Strategic Launch
The U.S. launch of PayRewards follows a period of intense competition in the B2B payment space. Established players such as Melio, BILL, and Plastiq have spent years educating the market on the benefits of digital payment workflows. However, PayRewards seeks to capture market share by leveraging its experience from the Australian market, where it is recognized as a leader in business payment rewards.
The $28 million funding round, announced in late August, provides the necessary capital for the firm to scale operations and navigate the complex U.S. regulatory landscape. According to statements made by the company’s leadership during the launch phase, the platform is designed to provide businesses with the flexibility to manage cash flow while simultaneously optimizing travel and loyalty budgets.
Regulatory Considerations and Tax Implications
One of the most complex aspects of using payment intermediaries for rewards is the tax treatment of the fees. While legitimate business expenses are generally tax-deductible under Internal Revenue Service (IRS) guidelines, the classification of "transaction fees" incurred to generate personal travel rewards is subject to scrutiny.
Under 26 U.S. Code § 162, expenses must be "ordinary and necessary" to the conduct of business. Tax experts warn that if a fee is inflated or if the primary purpose of the transaction is to accumulate points for personal travel rather than to facilitate a business payment, the IRS may challenge the deduction. This risk was underscored by a 2025 settlement between the U.S. Department of Justice and American Express, which touched upon the improper use of financial services to generate rewards, serving as a cautionary tale for businesses seeking to write off these processing fees.
Strategic Utility: Singapore Airlines and Cathay Pacific
The value of the PayRewards currency is tied to its transfer partners, currently headlined by Singapore Airlines (KrisFlyer) and Cathay Pacific (Asia Miles).
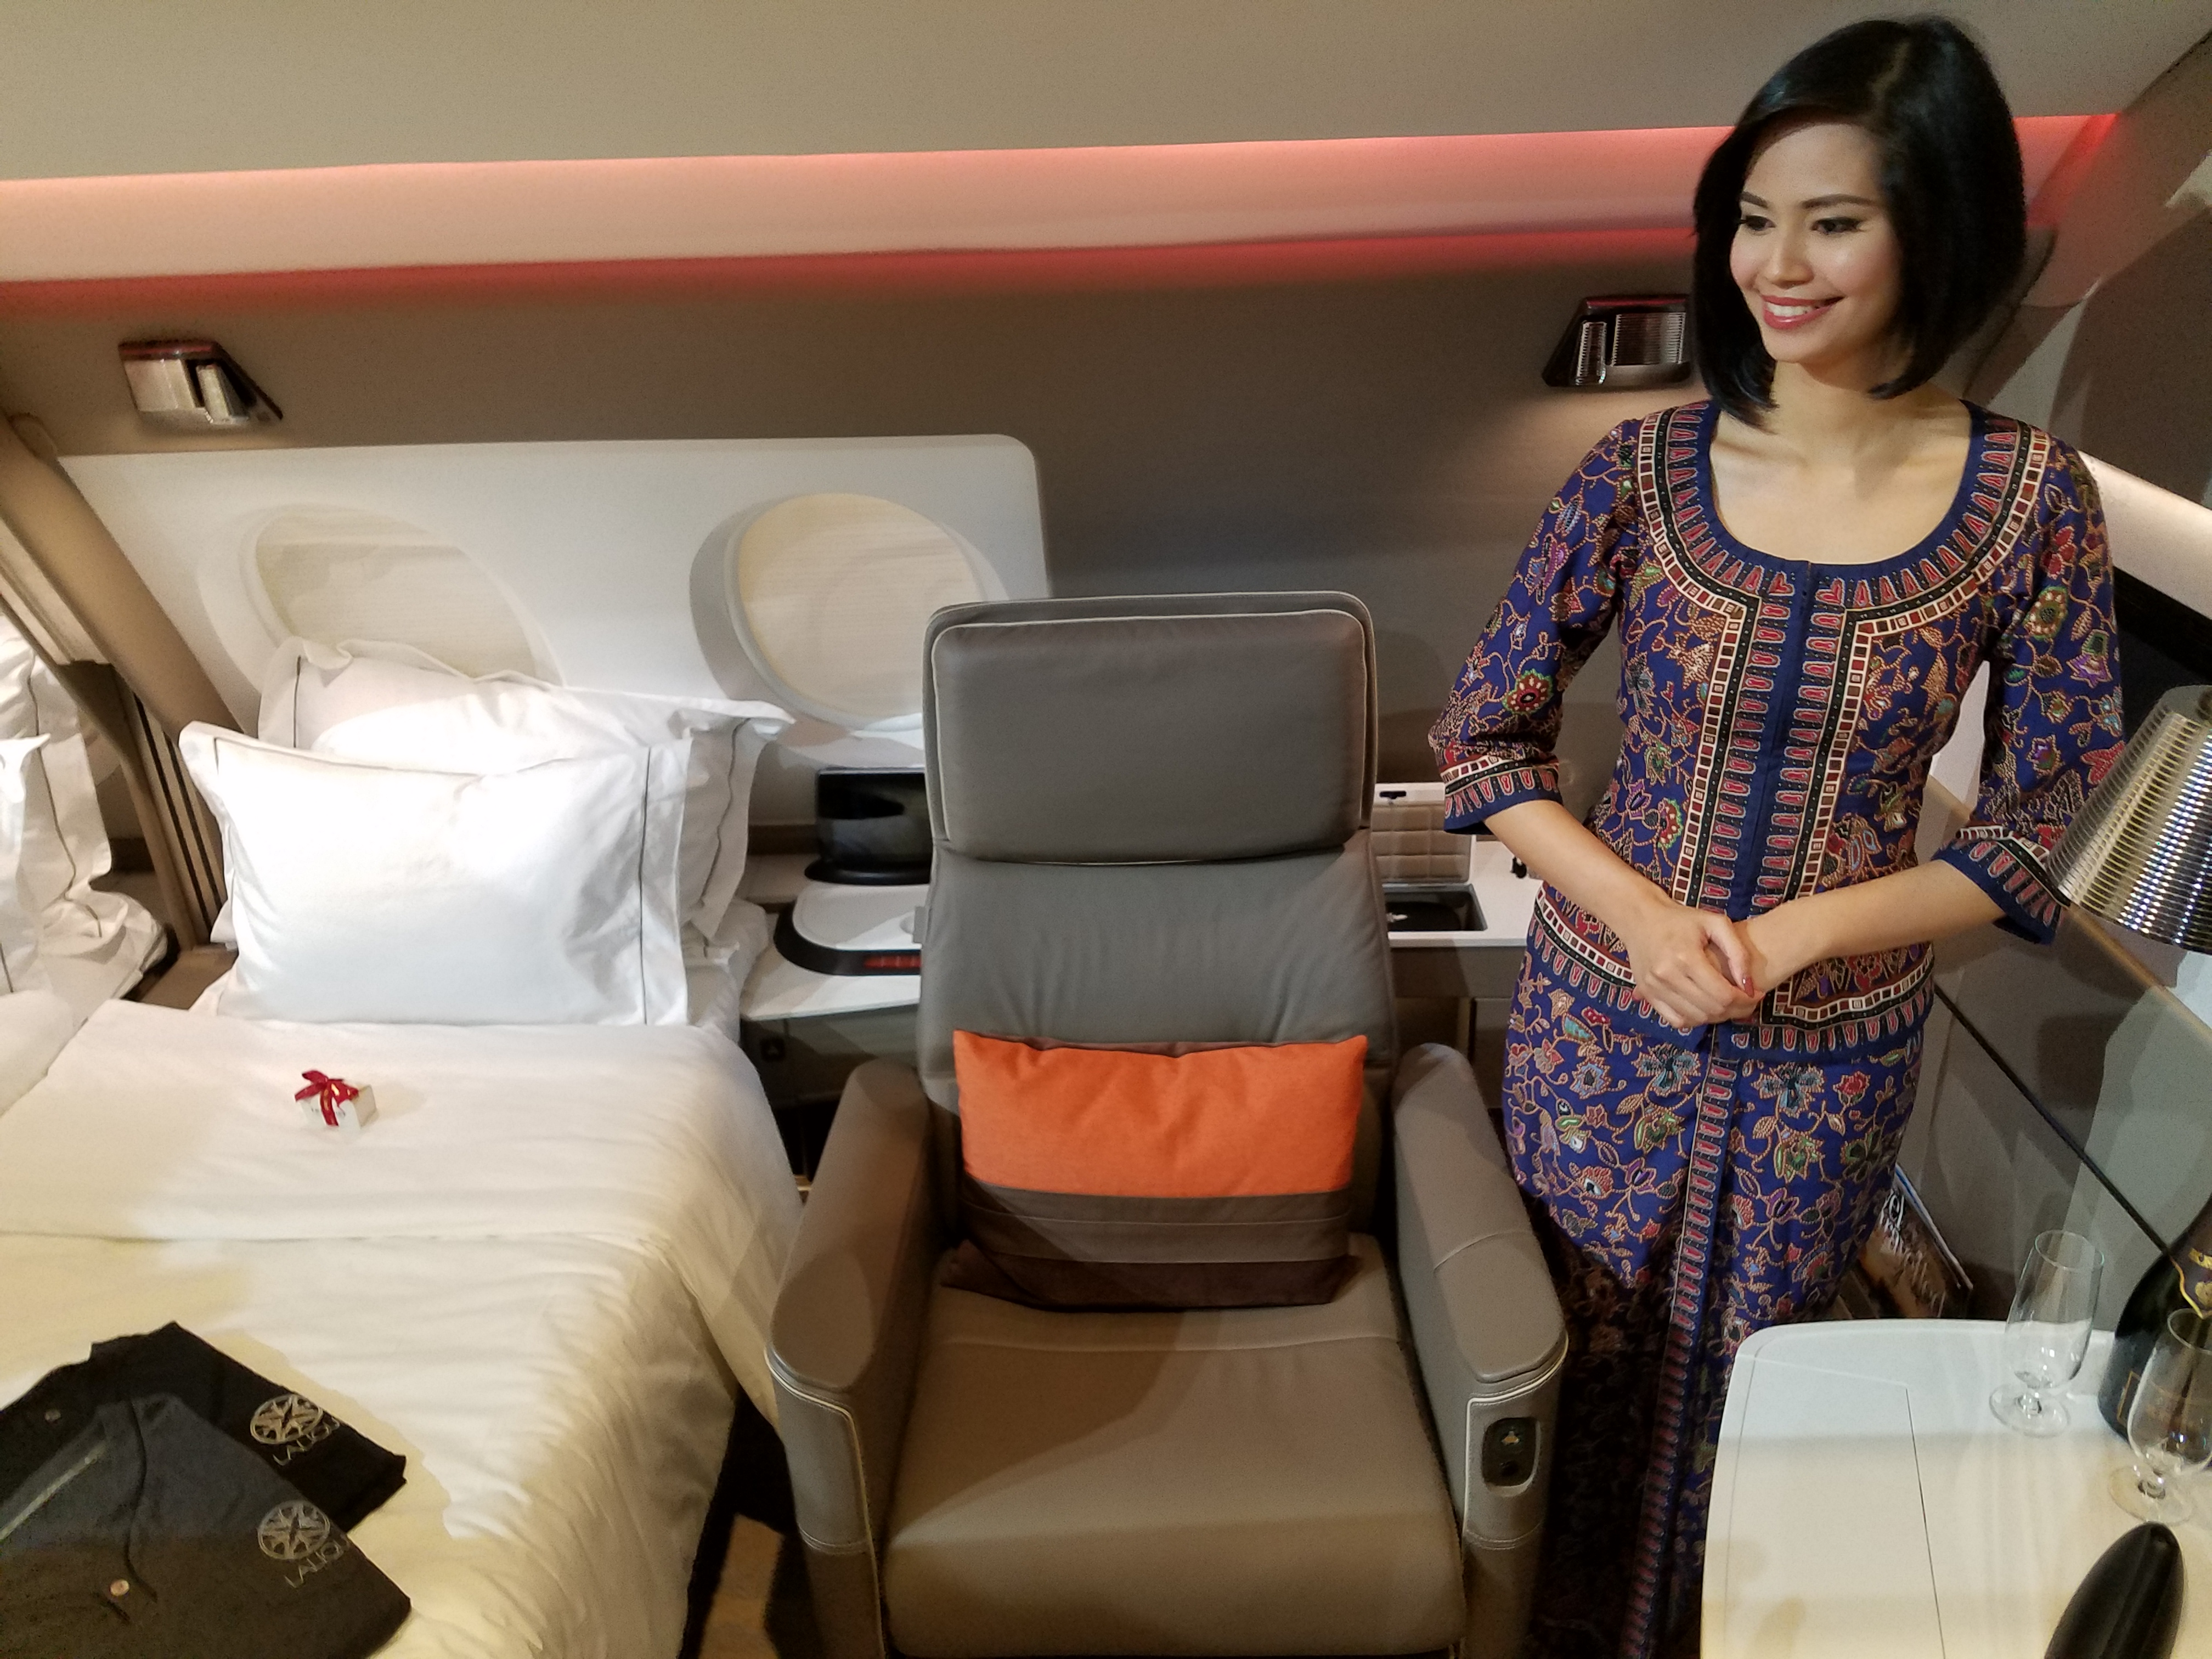
Singapore Airlines’ KrisFlyer program is widely considered one of the most valuable in the travel industry. It remains the exclusive channel for booking long-haul First Class and "Suites" availability on its flagship Airbus A380 aircraft. By accumulating points through business expenses, corporations can subsidize the cost of high-end travel for executives, which often commands price tags in the five-figure range.
Cathay Pacific’s Asia Miles, meanwhile, offers unique access to premium cabins that are often unavailable to partner airlines. Furthermore, it serves as an efficient tool for mitigating the high fuel surcharges often associated with British Airways bookings. By routing these bookings through Asia Miles, business travelers can significantly reduce the cash out-of-pocket costs typically required for international long-haul business class seats.
Operational Constraints and Geographic Availability
Despite the benefits, the platform is not available to all U.S. entities. At the time of the August launch, PayRewards listed several jurisdictions—including Connecticut, Hawaii, New Mexico, South Dakota, West Virginia, and Washington, D.C.—as ineligible for the service. These restrictions are likely tied to individual state-level money transmitter licensing requirements.
Furthermore, the platform enforces strict internal controls to prevent "circular payments." The terms of service explicitly prohibit users from paying themselves, family members, or affiliated entities. These safeguards are designed to prevent the platform from being used for manufactured spend, a practice that historically has led to account closures and increased regulatory scrutiny within the credit card industry.
Broader Implications for Corporate Finance
The emergence of PayRewards represents a shift in how small businesses view their accounts payable. By treating a supplier payment not just as a financial obligation but as a potential source of capital, companies are adopting a more integrated approach to corporate finance.
For a company with $1 million in annual vendor expenses that currently earns zero rewards, the ability to transition those payments to a credit card-based platform could yield millions of points annually. When utilized correctly, this could cover the entirety of a firm’s annual executive travel budget. However, the decision to utilize these services requires a rigorous cost-benefit analysis. Financial officers must weigh the 3% to 6% transaction fees against the actual market value of the rewards earned and the potential impact on their company’s tax liabilities.
As the industry matures, the competition between platforms like PayRewards, Melio, and Plastiq will likely result in lower transaction costs and more robust integration with existing accounting software, such as QuickBooks or Xero. For now, businesses interested in the platform are advised to verify their eligibility and conduct a trial transaction to ensure that the rewards gained align with their specific travel or financial objectives.
The service is currently positioned as a niche but powerful tool for businesses that are already active in the points-and-miles ecosystem. By providing a bridge between the rigid world of B2B billing and the high-value world of premium airline loyalty programs, PayRewards has established a clear value proposition for the modern, rewards-conscious business owner.