Wells Fargo Active Cash Card Named Best Credit Card for 2026 Due to Exceptional Flat-Rate Rewards and No Annual Fee

In the fiercely competitive landscape of personal finance and consumer credit, finding a financial instrument that balances simplicity with robust rewards can often feel like searching for a needle in a haystack. Financial analysts and industry experts continually review hundreds of options, weighing sign-up bonuses, variable percentage rates, annual fees, and supplementary perks. Following a comprehensive evaluation of the current market, the Wells Fargo Active Cash® Card has officially been crowned the Best Credit Card for 2026. This prestigious designation underscores the card’s enduring appeal, driven largely by its straightforward, lucrative flat-rate cash rewards structure and absence of an annual fee.
The Rise of Flat-Rate Cash Back in Modern Consumer Finance
Over the past decade, consumer preferences in credit card rewards have undergone a noticeable shift. While tiered rewards cards—which offer higher percentages in rotating categories such as dining, groceries, or travel—frequently attract early attention, they often demand significant tracking, category activation, and adherence to monthly spending caps. Consequently, a growing segment of consumers has gravitated toward flat-rate rewards cards. These products eliminate administrative friction, allowing users to earn a consistent percentage back on every single transaction, regardless of the merchant type.
When Wells Fargo introduced the Active Cash® Card, it immediately disrupted the flat-rate category by offering an unlimited 2% cash rewards rate on all purchases. This reliable return bypasses the need for cardholders to memorize spending calendars or calculate which card to pull from their wallets for specific purchases. As inflation and shifting economic conditions prompt consumers to scrutinize their household budgets more closely, the appeal of a seamless, high-yielding, no-annual-fee card has only intensified, ultimately propelling the product to its top-tier status for 2026.
Key Financial Features and Product Specifications

A closer examination of the Wells Fargo Active Cash® Card reveals a robust suite of features designed to cater to a wide demographic of consumers, ranging from disciplined budgeters to those managing short-term financing needs.
First and foremost is the earnings structure: cardholders receive an unlimited 2% cash rewards on purchases. Unlike competing products that taper off after a specific spending threshold or restrict high earnings to domestic transactions, the Active Cash structure imposes no limits on the total rewards accumulated over a calendar year.
Furthermore, the card features a competitive welcome offer. New applicants who are approved and spend $500 in purchases within the first three months of account opening earn a $100 cash rewards bonus. Within the industry, pairing a flat 2% rewards rate with a cash sign-up bonus is relatively uncommon, as many 2% cards traditionally omit introductory bonuses entirely.
To assist consumers managing upcoming expenses or consolidating debt, the card also incorporates a 0% introductory APR offer. New cardholders receive 0% intro APR for 12 months from account opening on both purchases and qualifying balance transfers. Once this 12-month promotional window concludes, a variable regular APR of 18.74%, 24.74%, or 28.74% applies, depending on the cardholder’s creditworthiness and prevailing market benchmarks.
Beyond standard financial metrics, the card includes practical consumer protections. Notably, it features built-in cell phone protection. Cardholders who charge their monthly cellular telephone bill to the Active Cash card can receive up to $600 in coverage against damage or theft, subject to a minor $25 deductible per claim. This added layer of utility elevates the card’s value proposition well beyond basic cash back accumulation.
Credit Score Requirements and Eligibility Guidelines
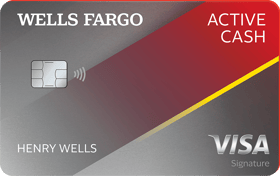
Securing approval for top-tier financial products generally requires meeting specific credit thresholds set by issuing banks. According to data provided by financial review boards, the recommended credit score required for the Wells Fargo Active Cash® Card falls into the "Good to Excellent" range, typically defined as a FICO score between 670 and 850.
While falling within this score range does not guarantee automated approval—as issuers evaluate broader financial metrics such as debt-to-income ratio, employment status, and overall credit history—it represents the baseline profile most likely to yield a favorable lending decision. Consumers working to rebuild their credit profiles are generally advised to explore dedicated credit-building tools before applying for premium rewards cards to avoid unnecessary inquiries on their credit reports.
Comparative Landscape: How It Compares to Industry Peers
To fully understand the significance of the Active Cash card’s top ranking for 2026, it is helpful to examine the broader competitive environment. Two notable alternatives frequently analyzed alongside the Wells Fargo offering are the Capital One Quicksilver Cash Rewards Credit Card and the Citi Double Cash® Card.
The Capital One Quicksilver card is widely recognized for its steady rewards structure and introductory offers, appealing to consumers seeking a reliable everyday card with flexible redemption options. Similarly, the Citi Double Cash card employs a unique dual-payment model, granting 1% cash back at the time of purchase and an additional 1% when paying off those purchases, effectively totaling 2% back.
However, the Wells Fargo Active Cash® Card distinguishes itself through its combination of an immediate 2% flat rate upon transaction settlement, an accessible welcome bonus, and robust secondary perks like cell phone insurance—all housed under a $0 annual fee framework. This balance minimizes friction for the end user, cementing its status as a preferred tool for streamlined personal finance management.
Strategic Implications for Consumers and Financial Health
As financial institutions navigate changing interest rate environments and shifting regulatory landscapes, the credit card market continues to innovate. For the everyday consumer, the selection of a primary payment card carries meaningful implications for household cash flow and purchasing power.
Financial advisors consistently emphasize that rewards cards are most effective when utilized as tools for planned expenditures rather than mechanisms for generating long-term debt. The presence of a 0% introductory APR period provides valuable breathing room for major purchases or balance consolidation, provided the user maintains a structured repayment strategy before the standard variable APR takes effect.
Moreover, transitioning from traditional debit cards to a rewards credit card like the Active Cash model offers distinct advantages in consumer protection. Credit cards generally provide superior fraud liability protections compared to debit cards, shielding personal checking accounts from immediate exposure during security incidents. When combined with the accumulation of steady cash rewards, responsible credit utilization transforms routine monthly spending into a micro-stream of passive savings.
Outlook and Conclusion
The recognition of the Wells Fargo Active Cash® Card as the Best Credit Card for 2026 highlights a broader consumer demand for transparency, simplicity, and tangible value. In an era where financial products frequently complicate reward redemption with tiered structures and restrictive partnerships, the appeal of a straightforward, unlimited 2% return remains unmatched. Backed by a competitive welcome offer, a year-long introductory APR window, and no annual fee, the card bridges the gap between high-end travel rewards and basic cash back simplicity. As consumers look ahead to manage their finances amidst evolving economic conditions, tools that maximize every dollar spent without imposing bureaucratic hurdles will undoubtedly remain the cornerstone of intelligent personal finance management.