The American Airlines Pilot Contract Is Helping Delta Win Austin—How Job Protection Backfired

The Strategic Retreat from the Texas Capital
For several years, American Airlines viewed Austin as its "love language," a rapidly expanding tech hub that offered the perfect demographic for a major focus city expansion. Between 2021 and 2022, the airline executed an ambitious growth plan, launching 24 new routes from the city to destinations across the United States, Mexico, and the Caribbean. Former Chief Commercial Officer Vasu Raja championed this strategy, arguing that connecting Austin directly to secondary markets would solidify the carrier’s AAdvantage loyalty program and drive credit card spending—a critical revenue stream in modern aviation.
However, the momentum stalled. As the post-pandemic travel surge settled into a new normal, American found itself unable to sustain the network density required to maintain its Austin footprint. In contrast, Delta Air Lines treated Austin as a long-term strategic focus city. While American retreated to its core hubs, Delta maintained its gate footprint, even flying low-utilization routes to hold ground until demand matured. This divergence in strategy has left American with a diminished presence while competitors effectively "squatted" on infrastructure, preparing for future capacity expansion.
Chronology of Austin Expansion and Contraction
The timeline of American’s Austin play reflects a volatile period in post-pandemic aviation strategy:
- March 2021: American Airlines announces a massive 10-route expansion from Austin, signaling its intent to capture the booming local market.
- June 2021: Building on the initial success, the carrier adds 14 additional destinations, attempting to position Austin as a secondary hub.
- October 2021: Executives emphasize that partnerships with Alaska Airlines and JetBlue are driving record AAdvantage enrollments in the region.
- November 2021: Plans for a new Admirals Club lounge are unveiled, signaling a long-term commitment to the airport’s infrastructure.
- 2023: Faced with mounting operational costs and the inability to deploy smaller, more efficient regional jets on point-to-point routes, American begins a systematic dismantling of its Austin focus city, cutting 21 routes.
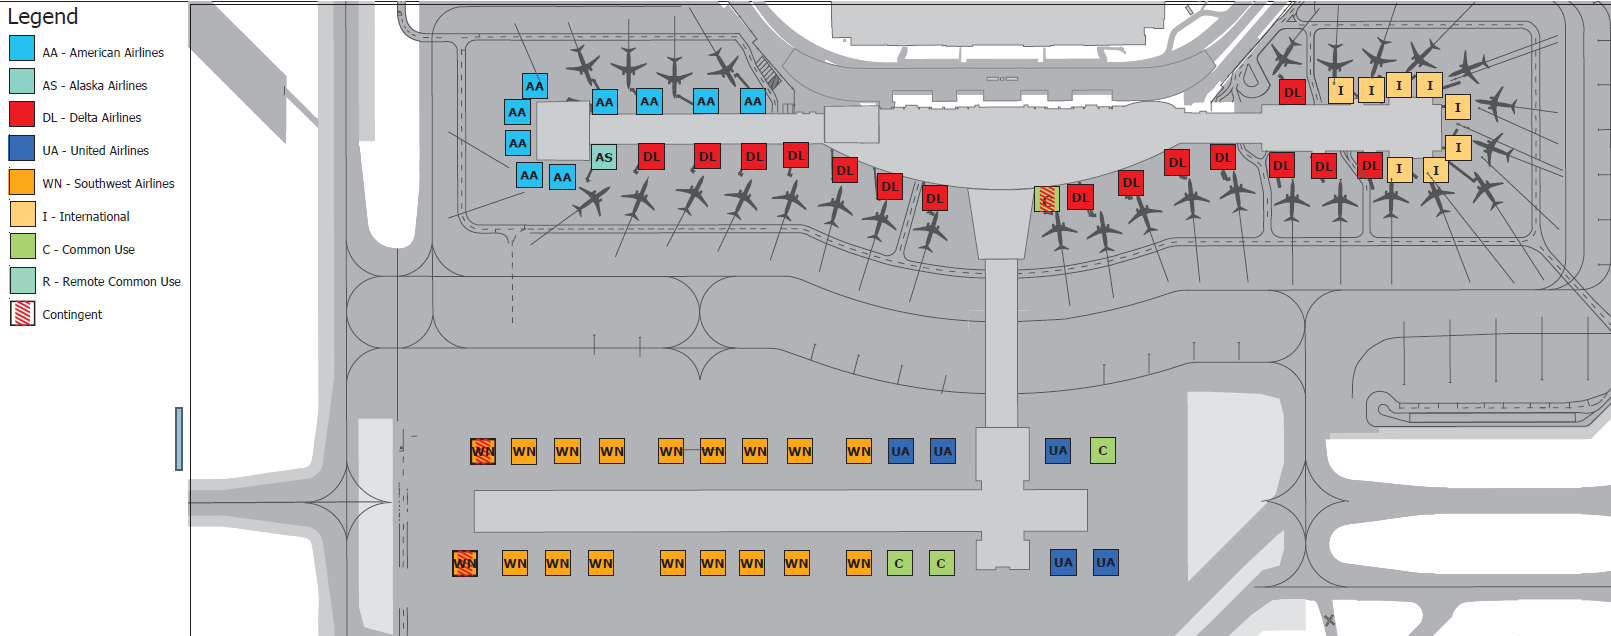
- 2025–2026: Under a new airport use and lease agreement, American secures a commitment for nine gates, but these will not be fully operational until the new concourse opens in the 2030s.
The Role of Pilot Scope Clauses
The primary technical hurdle for American in Austin is the current pilot contract. These agreements contain "scope clauses" that strictly regulate the use of regional jets (RJs). Typically, these contracts mandate that a significant portion of small-jet flying must be tied to legacy hubs. This prevents American from utilizing its regional fleet to "test" or "develop" thinner routes from cities like Austin that do not originate from its primary hubs (such as Dallas-Fort Worth, Charlotte, or Miami).
Without the ability to deploy smaller aircraft, American is forced to choose between flying expensive, 150-plus seat mainline aircraft—which are difficult to fill on new, unproven routes—or not flying the route at all. This creates a "profitability trap." If the airline flies a half-empty mainline plane, it loses money; if it pulls the route, it loses market share and loyalty card acquisitions to competitors like Delta, who possess greater flexibility in their regional operations or are better equipped to sustain early-stage losses.

Industry analysts have long pointed to this as a competitive disadvantage. Scott McCartney, a veteran aviation journalist, recently noted on the Airlines Confidential podcast that the restriction on regional jets is a self-imposed handcuff. The pilots’ union, for its part, has historically guarded these scope clauses to ensure that regional flying does not replace higher-paid mainline jobs. However, this protective measure has a secondary effect: it limits the airline’s total growth potential, which in turn limits the long-term number of mainline pilot positions available as the market matures.
The Financial Nexus: Loyalty and Credit Cards
The modern airline business model has shifted from selling seats to selling miles. Airlines are increasingly "credit cards with wings," where the majority of profit is derived from co-branded credit card spend and loyalty program participation. Delta CEO Ed Bastian has been transparent about this, identifying Austin as a primary target for American Express card acquisitions.
By pulling back from Austin, American is not just losing flight revenue; it is losing the ability to sign up new AAdvantage members who provide the high-margin, recurring revenue that Wall Street rewards. As American retreats, it cedes the Austin demographic to Delta and Southwest, making it increasingly difficult to win those customers back in the future. The decision to scale back is, therefore, not just an operational choice but a significant long-term hit to the company’s loyalty ecosystem.
Future Outlook and Contract Negotiations
There is a potential path forward. American Airlines’ pilots have opened contract negotiations early, with the current deal becoming amendable in August 2027. Union leadership, led by Nick Silva, has expressed frustration with current management’s performance, arguing that the company is only now focusing on the customer experience after years of underinvestment.
The negotiation period presents a unique opportunity to modernize the scope clauses. If the union and management can agree on "market-specific flexibility"—where the airline is granted permission to use regional jets in developing markets like Austin or San Jose in exchange for guaranteed future mainline growth—the carrier could potentially regain its competitive footing.
However, time is a luxury American does not have. The new midfield concourse at Austin-Bergstrom is slated for completion in the 2030s, and the airport’s new use and lease agreement mandates minimum gate usage. American is currently allocated nine gates, while Delta and Southwest have secured 15 and 18, respectively. If American cannot figure out how to bridge the gap between its current contract restrictions and the future demand of the Austin market, it risks being a permanent third-place player in one of the fastest-growing aviation markets in the United States.
Implications for Stakeholders
The current situation serves as a warning for both management and labor. For management, the failure to anticipate the conflict between the Austin expansion and existing contract limitations resulted in wasted capital and a damaged brand reputation in the Texas capital. For the pilots’ union, the rigidity of scope clauses, while intended to protect jobs, has inadvertently limited the carrier’s ability to grow into profitable new segments, thereby stifling potential long-term career growth.
As the industry moves toward 2027, the success of American Airlines will likely hinge on its ability to move beyond the adversarial dynamics of the past and craft a labor agreement that reflects the modern reality of the airline industry—a reality where growth is driven by flexibility, loyalty, and the ability to pivot rapidly in response to market demand. Whether American can reclaim its "love language" in Austin will depend entirely on whether it can align its contractual obligations with the competitive requirements of the 21st-century aviation landscape.