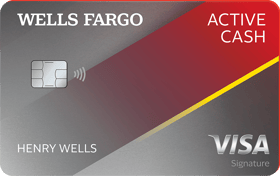
In the rapidly evolving landscape of personal finance and consumer credit, finding a financial product that balances simplicity with maximum monetary return is often a challenge for everyday shoppers. As financial institutions continuously adjust their portfolios to meet the demands of inflation-conscious consumers, flat-rate cash back cards have re-emerged as a preferred choice for budget-minded individuals. Among the crowded field of no-annual-fee options, the Wells Fargo Active Cash® Card has officially captured the designation of Best Credit Card for 2026 by industry experts, setting a high standard for everyday consumer value.
The Evolution of Flat-Rate Cash Back Rewards
For years, credit card rewards programs were dominated by tiered structures that required consumers to track rotating quarterly categories, navigate complex mobile applications, and worry about spending caps. While these niche cards can yield high returns for hyper-organized users, they often alienate the average consumer who prefers a seamless purchasing experience.
The introduction of the flat-rate reward mechanism marked a significant paradigm shift in the credit industry. By offering a predictable percentage back on every transaction regardless of the merchant type, issuers eliminated the mental friction associated with earning rewards. Wells Fargo entered this competitive arena with a straightforward proposition: an unlimited 2% cash rewards structure on all purchases. This consistency has resonated strongly with consumers looking for reliable, hands-off value, propelling the Active Cash card to the forefront of the market as financial planners and consumer advocates look ahead to the 2026 economic environment.
Core Features and Financial Mechanics
At the heart of the card’s appeal is its lack of spending categories to activate or limits to track. Cardholders earn a flat 2% back on everything from utility bills and groceries to major electronic purchases. This structural simplicity avoids the pitfalls of capped rewards programs, where high spenders frequently hit maximum thresholds mid-year and stop earning bonus returns.

Beyond its continuous earning potential, the card incorporates several auxiliary financial tools that make it a comprehensive wallet staple. New cardholders gain access to a welcome bonus of $100 after spending $500 on purchases within the first three months of account opening. While some premium travel and rewards cards offer larger sign-up bonuses, they typically come with steep annual fees or high minimum spending requirements that can tempt consumers into overspending. The modest $500 threshold on the Active Cash card is designed to be easily attainable for ordinary household budgets.
Furthermore, the product features an introductory 0% APR period lasting 12 months from account opening on both new purchases and qualifying balance transfers. After this promotional window concludes, a variable regular APR ranging from 18.74%, 24.74%, to 28.74% applies based on creditworthiness. This introductory period offers substantial utility for cardholders aiming to finance large upcoming expenditures or consolidate existing high-interest debt without incurring immediate finance charges.
Consumer Protection and Additional Benefits
In addition to its rewards and introductory financing terms, the Wells Fargo Active Cash Card incorporates consumer protection policies that add tangible value to everyday transactions. One notable inclusion is built-in cellular telephone protection. By utilizing the card to pay monthly mobile phone bills, eligible cardholders can receive up to $600 in coverage against damage or theft, subject to a $25 deductible. Given the rising cost of modern smartphones—frequently exceeding $1,000—this embedded insurance policy offers a practical alternative to costly carrier-sponsored device protection plans.
The absence of an annual fee further reduces the risk profile of the card for cautious financial managers. Unlike rewards cards that charge $95 to $550 annually, requiring the user to continuously calculate whether the rewards outweigh the upfront cost, a $0 annual fee ensures that every dollar earned is net profit for the consumer.
Credit Score Requirements and Target Demographics
Securing approval for the Wells Fargo Active Cash Card generally requires a good to excellent credit history, translating to a FICO score typically falling within the 670 to 850 range. While meeting this credit threshold does not guarantee approval—as issuers evaluate comprehensive financial profiles including debt-to-income ratios and employment status—it serves as the baseline benchmark for prospective applicants.
Financial analysts note that the card serves as a natural upgrade for consumers currently relying on traditional debit cards for daily transactions. While debit cards draw funds directly from checking accounts, they typically lack the robust fraud liability protections mandated for credit cards and rarely offer meaningful rewards programs. By transitioning everyday spending to a secure, rewards-generating credit card managed responsibly, consumers can enhance their financial security while accumulating modest passive returns.
Comparative Market Analysis: How It Stacks Up
To understand the positioning of the Wells Fargo Active Cash Card within the broader financial ecosystem, it is helpful to examine competing products offered by other major financial institutions.
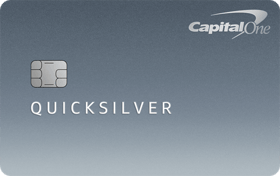
The Capital One Quicksilver Cash Rewards Credit Card represents a prominent alternative in the flat-rate rewards space. It typically offers a competitive welcome bonus and a structured introductory APR period, though its baseline rewards rate generally hovers around 1.5% cash back on all purchases, compared to the 2% flat rate provided by Wells Fargo. For consumers whose spending volume is sufficiently high, the additional 0.5% return on the Active Cash card can accumulate into significant annual savings.
Another notable competitor is the Citi Double Cash® Card, which also features a 2% cash back structure. However, the Citi product structures its earnings as 1% at the time of purchase and an additional 1% upon paying off those purchases, encouraging prompt payment behavior. In contrast, Wells Fargo awards the full 2% at the time of transaction settlement, offering a more immediate realization of rewards.
Broader Economic Implications and Expert Guidance
The prominence of high-yielding, no-fee credit cards reflects broader economic trends characterized by heightened consumer selectivity. As households navigate fluctuating interest rates and cost-of-living pressures, financial products that deliver transparent, guaranteed value without hidden costs have captured market share from complex reward ecosystems.
Industry experts emphasize that while rewards and promotional APR offers are powerful financial instruments, they should be utilized with discipline. Financial literacy organizations consistently advocate for the "pay-in-full" philosophy: treating a rewards credit card strictly as a payment medium rather than a source of revolving credit. Carrying a balance at standard variable interest rates can rapidly eclipse any cash back earned through daily spending, negating the financial advantages of the card.
Ultimately, the recognition of the Wells Fargo Active Cash Card as a leading financial product for 2026 underscores a consumer preference for straightforward utility. By merging unlimited flat-rate earnings, an achievable welcome bonus, zero annual fees, and essential consumer protections, the card provides a balanced template for modern personal financial management.