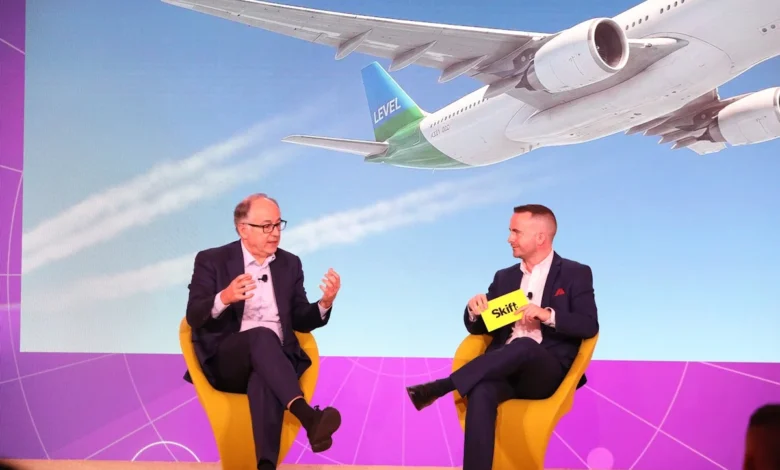
International Airlines Group (IAG) Chief Executive Officer Luis Gallego recently took center stage at the Skift Aviation Forum to outline how modern, large-scale aviation conglomerates can successfully navigate persistent industry headwinds, including volatile jet fuel prices and unpredictable demand cycles. Moderated by Skift Airlines Editor Gordon Smith, the discussion offered a masterclass in corporate resilience, strategic capital allocation, and the structural advantages of operating a diversified portfolio of airlines under a single, centralized parent organization.
As the global aviation sector continues to grapple with macroeconomic pressures, geopolitical instability, and environmental transition mandates, Gallego’s insights provide a timely blueprint for how legacy carriers and multi-airline groups can future-proof their operations. The core takeaway from the high-profile session is that navigating turbulent market conditions requires a rigorous, disciplined approach to distributing capital across distinct geographic markets and varied business models, ranging from low-cost carriers to premium long-haul operators.
The Context of the Skift Aviation Forum and Industry Pressures
The Skift Aviation Forum has long served as a premier gathering place for industry leaders, innovators, and analysts to dissect the most pressing challenges facing commercial aviation. Set against a backdrop of post-pandemic recovery and mounting economic uncertainty, the latest installment of the forum focused heavily on adaptability. Airlines globally have faced a grueling few years characterized by soaring inflation, supply chain bottlenecks for new aircraft and spare parts, labor shortages, and, most notably, extreme fluctuations in the cost of jet fuel.
Jet fuel traditionally represents one of the single largest variable operating expenses for any airline, frequently accounting for between 20% and 30% of total operating costs depending on market conditions. When crude oil prices spike due to geopolitical conflicts, supply cuts by major producers, or sudden surges in global demand, airline operating margins can evaporate almost overnight. For standalone carriers, a sudden fuel price shock can be catastrophic, often forcing emergency measures such as capacity cuts, fare hikes, or emergency debt financing.
However, as Gallego detailed during his keynote session, large airline groups structured like IAG—which counts British Airways, Iberia, Vueling, Aer Lingus, and Level among its portfolio—enjoy structural cushions that individual carriers simply do not possess. By pooling resources, centralizing back-office functions, and sharing best practices across disparate brands, IAG has managed to weather economic storms while continuing to invest in long-term strategic initiatives, such as fleet modernization and sustainable aviation fuel (SAF) procurement.
The Mechanics of Centralized Capital Allocation and Diversified Operations
At the heart of Gallego’s presentation was a detailed explanation of how IAG balances centralized corporate governance with operational autonomy for its individual airline brands. Managing a portfolio that includes a premium flag carrier like British Airways alongside low-cost entities like Vueling requires a delicate balancing act.
Under IAG’s operational model, individual airlines retain the freedom to pursue distinct commercial strategies tailored to their specific customer bases and regional markets. British Airways can focus on high-yield corporate and long-haul leisure travel, Iberia can capitalize on the lucrative and rapidly growing traffic flows between Europe and Latin America, and Vueling can target cost-conscious European short-haul travelers. This market diversification ensures that a downturn in one specific region or customer segment does not drag down the entire corporate group.
Simultaneously, capital allocation decisions are strictly centralized at the holding company level. Operating companies do not automatically receive funding based on historical precedent or brand prestige. Instead, individual airlines within the IAG umbrella must actively compete for corporate capital by demonstrating robust projected returns on investment. This internal market discipline ensures that shareholder funds are directed toward the most profitable and strategically sound projects, whether that involves acquiring fuel-efficient next-generation aircraft, upgrading digital infrastructure, or expanding high-margin route networks.
According to Gallego, this rigorous framework has been instrumental in helping the group absorb sudden cost shocks. When fuel prices spike, the centralized treasury can deploy hedging strategies at scale, securing more favorable pricing terms than individual airlines could achieve on their own. Furthermore, the diversified revenue streams allow the group to offset margin compression in one subsidiary with strong performance in another, maintaining overall financial stability.
Historical Evolution and Chronology of IAG’s Growth Strategy
To fully appreciate the resilience demonstrated by IAG today, it is essential to examine the historical trajectory of the group. Formed in January 2011 through the formal merger of British Airways and Iberia, IAG was designed from its inception to be a multi-brand consolidator capable of reshaping the European and global aviation landscape.
The rationale behind the merger was clear: traditional European legacy carriers were struggling to compete against aggressive low-cost carriers on short-haul routes while facing heavy regulatory burdens and high cost bases. By combining forces, British Airways and Iberia could achieve immediate cost synergies in procurement, maintenance, and administration while preserving their respective national identities and hub structures.

Over the subsequent decade and a half, IAG systematically expanded its portfolio. The group acquired Spanish low-cost carrier Vueling in 2013, followed by the acquisition of Irish flag carrier Aer Lingus in 2015. More recently, the group has incubated and grown Level as a low-cost long-haul brand based out of Barcelona, further diversifying its market reach.
Throughout this chronological expansion, the underlying management philosophy remained consistent: centralization of strategic oversight coupled with decentralized operational execution. This approach allowed the group to survive the unprecedented crisis of the COVID-19 pandemic between 2020 and 2022—during which global air travel ground to a near-total halt—and emerge in a position of financial strength. By maintaining strict cost control, restructuring debt, and leveraging its multi-brand model, IAG rebounded faster than many of its European competitors, posting robust profitability in the post-pandemic travel boom.
Supporting Data: The Financial Realities of Modern Airline Management
Industry analysts and financial metrics underscore the wisdom of Gallego’s strategic focus on capital discipline and diversification. According to recent financial reports issued by IAG, the group has consistently prioritized balance sheet strength, aiming to reduce net debt and maintain strong liquidity buffers to guard against future macroeconomic shocks.
In the broader aviation sector, data from the International Air Transport Association (IATA) highlights the persistent vulnerability of airlines to external cost pressures. Fuel expenses remain one of the most volatile variables in airline financial forecasting. In periods where jet fuel prices surge by even 10% to 15%, industry-wide profitability can drop by billions of dollars unless offset by immediate yield management strategies, such as raising ticket prices or implementing fuel surcharges.
However, IAG’s financial disclosures have frequently demonstrated that its diversified model dampens the severity of these shocks. For instance, while high fuel prices pressure short-haul margins—where low-cost competition limits the ability to pass costs entirely onto the consumer—strong demand for premium long-haul travel can often compensate. By capturing high-yield passengers traveling across the Atlantic and between Europe and Latin America, premium brands like British Airways and Iberia provide the cash flow necessary to sustain group-wide investments.
Furthermore, capital expenditure data reveals that IAG has poured billions of euros into fleet renewal programs. Transitioning away from older, fuel-guzzling aircraft in favor of modern widebody and narrowbody planes—such as the Airbus A350, Boeing 787 Dreamliner, and Airbus A320neo family—has been a cornerstone of the group’s fuel-efficiency strategy. Modern aircraft typically deliver a 15% to 25% reduction in fuel consumption and carbon emissions compared to the older models they replace, providing a structural defense against high fuel prices that goes far beyond short-term financial hedging.
Industry Reactions and Perspectives from Financial Markets
Financial analysts and aviation experts have largely praised IAG’s disciplined capital allocation model, viewing it as a benchmark for airline holding companies worldwide. Competitor airline groups, such as Air France-KLM and the Lufthansa Group, have similarly pursued multi-brand consolidation strategies, recognizing that standalone national carriers face mounting disadvantages in a globalized, highly competitive market.
Market observers note that Gallego’s emphasis on internal competition for capital creates a healthy Darwinian environment within the corporate group. Operating companies cannot afford to rely on complacency; they must continuously optimize their cost structures, improve operational reliability, and enhance the customer experience to secure funding for future growth initiatives. This internal accountability resonates well with institutional investors, who are increasingly wary of capital-intensive industries with historically low returns on invested capital.
At the same time, labor unions and employee representatives have occasionally voiced caution regarding the intense focus on cost efficiency and return on capital. Balancing the financial demands of a strict corporate holding structure with the operational realities and morale of frontline workers remains a perpetual challenge for airline executives. Nevertheless, management has maintained that securing the long-term financial health of the group is the most effective way to protect jobs and ensure sustainable career paths for employees across all subsidiary airlines.
Broader Market Implications and What to Watch Moving Forward
The strategies articulated by Luis Gallego at the Skift Aviation Forum carry profound implications for the future trajectory of the global aviation industry. As airlines worldwide confront a complex operating environment defined by high interest rates, volatile energy markets, and tightening environmental regulations—such as European mandates for the increased blending of sustainable aviation fuel—the traditional standalone airline model is increasingly looking obsolete.
Industry observers and investors are advised to monitor several key indicators regarding IAG’s performance and the broader sector’s evolution:
- Fleet Modernization Paces: Watch how quickly IAG and other major airline groups take delivery of next-generation, fuel-efficient aircraft to permanently lower their baseline fuel consumption and carbon footprints.
- Regulatory Hurdles for Consolidation: Keep an eye on antitrust regulators in Europe and beyond, as ongoing efforts to consolidate the airline industry face heightened scrutiny over market dominance and consumer pricing.
- SAF Integration and Cost Passing: Observe how airlines manage the transition to Sustainable Aviation Fuel (SAF), which currently remains significantly more expensive than conventional jet fuel. The ability to pass these compliance costs onto consumers through premium pricing or corporate partnerships will be critical for maintaining profit margins.
- Geopolitical and Macroeconomic Shifts: Monitor crude oil price movements and regional economic indicators, particularly in key markets like the United Kingdom, Spain, and North America, which directly dictate premium travel demand and corporate budgets.
Ultimately, the insights shared by Luis Gallego underscore a fundamental truth of modern commercial aviation: survival and prosperity belong not to the biggest or the oldest carriers, but to those that can combine strategic agility, rigorous financial discipline, and a diversified operational footprint to weather whatever turbulence lies ahead.