The global travel and tourism sector is currently navigating a complex economic paradox where declining consumer interest and falling search volumes are being entirely masked by resilient, elevated pricing models across airlines and hospitality providers. According to the latest metrics released in the Skift Travel Health Index for September 2026, consumer intent to travel has visibly contracted across major international markets. Yet, despite fewer travelers actively searching for trips and a measurable dip in forward-looking planning, industry revenues have not yet hit bottom. This resilience at the financial top-line is primarily sustained by persistently high airfares and accommodation rates that continue to offset softening booking volumes.
The broader implications of this trend point toward a market under pressure. While revenue figures remain stable for the time being, industry analysts and economists are closely monitoring whether sustained high pricing can indefinitely withstand the cooling momentum in consumer demand. As the peak summer travel season transitions into the shoulder months of the autumn calendar, stakeholders across the aviation, hospitality, and destination marketing sectors are reassessing their pricing strategies and forward projections to prepare for potential headwinds.
Key Findings of the September 2026 Index
The Skift Travel Health Index stood at an aggregate score of 99 for September 2026, marking a 1% decline compared to the same period in the previous year. While a one-point dip on a baseline-adjusted index might appear modest at first glance, the underlying components reveal a more pronounced divergence between consumer desire and actual spending.
Most notably, the destinations index—which relies heavily on online search activity to gauge forward-looking consumer interest—suffered a steep 12% year-on-year drop, landing at 88. This sharp contraction was driven primarily by weakened inbound flight and hotel searches across the majority of tracked global markets. Consumers are clearly pausing their research phase, signaling a hesitation to commit to future travel plans amid ongoing macroeconomic uncertainties, inflationary pressures, and fatigue from prolonged high prices.
Despite this cooling in consumer search behavior, travel providers have maintained robust pricing power. Airlines and hotel operators have chosen to protect their margins by keeping fares and nightly rates elevated, successfully extracting higher yields from a smaller pool of active travelers. Consequently, gross revenues have held steady, creating a deceptive veneer of health that masks the underlying deceleration in booking velocity and consumer engagement.
Chronology and Evolution of Post-Pandemic Travel Dynamics
To understand the current trajectory of the global travel economy in late 2026, it is essential to examine the sequence of events that shaped the post-pandemic recovery and subsequent stabilization phases.
The initial phase, spanning from 2021 through 2023, was defined by pent-up demand commonly referred to as revenge travel. Consumers flooded the market, eager to reclaim mobility regardless of rising costs. During this period, airlines and hotels experienced historic surges in demand, enabling them to rapidly raise prices to repair balance sheets damaged by prolonged global lockdowns.
By 2024 and 2025, the market began to enter a normalization phase. While travel volumes remained high, the initial frenzy subsided, giving way to more price-sensitive consumer behavior. Inflationary pressures began to eat into disposable incomes, prompting travelers to seek out value, shorten trip durations, or explore closer-to-home domestic alternatives.
By mid-2026, cumulative price fatigue reached a critical threshold. Consumers began scaling back on preliminary travel planning, reflected directly in the double-digit drop in inbound search volumes recorded by the Skift Travel Health Index. Yet, resilient corporate travel demand and lingering luxury spending prevented an immediate collapse in ticket and room prices, creating the current holding pattern where volume declines are systematically balanced by premium pricing.
Granular Data Analysis and Regional Divergences
A
deeper dive into the regional data for September 2026 highlights significant disparities in how different parts of the world are experiencing this cooling trend. While Western markets have experienced notable dips in consumer enthusiasm, select Asian and emerging markets continue to display pockets of growth, preventing a uniform global downturn.
Inbound flight search metrics analyzed in the September 2026 report reveal that while traditional long-haul corridors from North America and Europe into popular Mediterranean and transatlantic hubs experienced noticeable slowdowns, certain destinations bucked the trend. China, for instance, registered positive year-on-year growth in inbound flight searches (+), pointing to a gradual but steady return of international visitors drawn by recent visa-free entry policies and aggressive tourism marketing campaigns launched by municipal and national authorities.
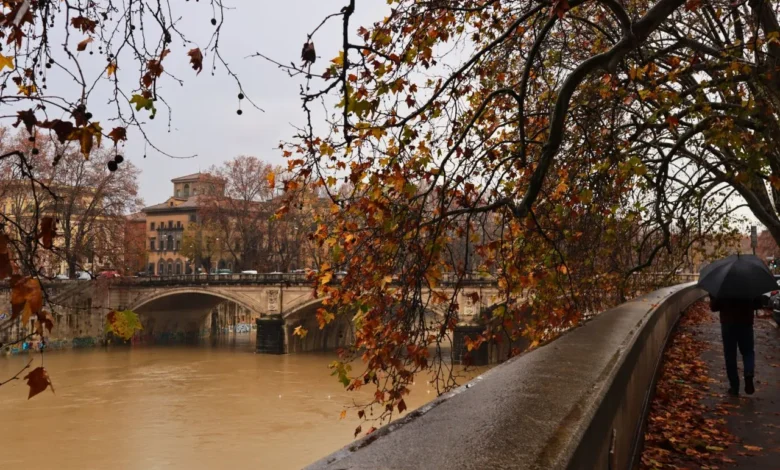
Conversely, mature leisure destinations across Europe witnessed a more pronounced cooling effect as local autumn weather set in and the financial strain of the summer peak season caught up with households. The Tiber River banks in Rome and other iconic European city-break locations saw steady foot traffic from travelers who had booked months in advance, but forward-looking digital engagement metrics suggested that autumn and winter bookings would face a tougher climb.
Industry Reactions and Corporate Strategies
The widening gap between declining search interest and resilient revenues has prompted varied responses from travel executives, hospitality groups, and aviation leaders.
Major airline executives speaking at recent industry forums have emphasized capacity discipline as the primary mechanism for maintaining profitability. Rather than engaging in fare wars to stimulate sluggish demand—a tactic common in past economic cycles—carriers are closely managing seat supply to match the cooler, more rationalized level of consumer interest. By keeping capacity tight, airlines ensure that load factors remain healthy even if total passenger counts grow at a slower rate than in previous years.
Similarly, international hotel chains have reported that while booking windows are shortening—with guests reserving rooms much closer to their actual travel dates—average daily rates (ADR) have remained stable or grown marginally. High-end and luxury segments continue to outperform midscale and economy properties, suggesting that wealthier travelers remain insulated from broad economic pressures, whereas budget-conscious consumers are postponing or canceling trips altogether.
Destination Management Organizations (DMOs) are also adapting their promotional strategies. Recognizing that generic inspirational marketing is yielding fewer online searches, tourism boards are pivoting toward targeted campaigns that emphasize high-value experiences, off-season travel benefits, and personalized itineraries designed to convert hesitant browsers into confirmed bookers.
Economic Implications and Future Outlook
The current state of the global travel industry as captured in the September 2026 data carries profound implications for the broader macroeconomic landscape. Travel and tourism remains a critical engine of job creation, foreign exchange earnings, and small business support. Therefore, any prolonged disconnect between high prices and cooling demand warrants careful analysis.
If travel providers maintain elevated pricing in the face of falling search volumes for too long, they risk accelerating a tipping point where consumers completely reject prevailing rates, leading to sharper, more painful corrections in revenue. Conversely, a managed soft landing—where inflation cools, prices stabilize at sustainable levels, and consumer confidence rebounds—could pave the way for a more balanced and durable growth cycle heading into 2027.
Financial analysts note that while the top-line revenue figures for Q3 2026 are likely to satisfy Wall Street and institutional investors in the short term, corporate leadership teams must remain agile. Cost management, operational efficiency, and dynamic pricing algorithms will be critical tools for navigating an environment where volume growth is no longer guaranteed.
As the industry looks ahead to the final quarter of the year and the crucial holiday booking season, all eyes will be on whether consumer sentiment stabilizes or if the cooling trend documented in September deepens. For now, the global travel economy continues to defy gravity, sustained by a delicate equilibrium between weary consumers and resolute pricing strategies.
Related posts: