The Digital Divide: How Cryptocurrency is Upending Modern Divorce Proceedings and Asset Division

Dividing marital assets during a divorce has historically involved sorting through traditional financial instruments such as real estate deeds, retirement accounts, corporate stock portfolios, and checking or savings statements. However, the widespread adoption of decentralized digital currencies has introduced a turbulent new frontier to family law. Family law attorneys, forensic accountants, and state courts are increasingly grappling with how to identify, trace, value, and equitably distribute cryptocurrency holdings during high-stakes marital dissolutions.
The integration of digital assets into domestic relations law represents one of the most complex procedural shifts in modern jurisprudence. Because blockchain networks allow assets to bypass traditional banking institutions entirely, separating spouses now possess unprecedented avenues to conceal wealth, obscure financial transactions, and complicate property settlements. As courts scramble to establish standardized frameworks, legal professionals are forced to adapt rapidly to an asset class that defies traditional geographic boundaries and jurisdictional oversight.
The Growing Prevalence of Crypto in Family Law
Cryptocurrency has evolved from a niche technology favored by tech enthusiasts into a mainstream financial asset held by millions of Americans. According to the 2026 CryptoCurrency Adoption and Sentiment Report, approximately 30 percent of adults in the United States own some form of digital currency. Demographically, ownership is heavily concentrated among younger generations, with individuals aged 30 to 44 forming the single largest demographic block, accounting for an estimated 23.5 million crypto owners nationwide.
This demographic reality directly impacts family law courts. Millennial and Gen Z couples experiencing marital breakdowns are far more likely to possess digital portfolios than older generations. Alphonse Provinziano, managing partner of Provinziano & Associates in Beverly Hills, California, notes that he is already observing a sharp spike in divorce cases where one spouse holds cryptocurrency while the other scrambles to locate and evaluate the holdings.
According to Provinziano, battling ex-spouses who have accumulated substantial crypto wealth are frequently reluctant to disclose the true extent of their digital portfolios. In many instances, withholding this information stems from a desire to shield the assets from equitable distribution laws. Because cryptocurrency is projected to remain a dominant asset class, Provinziano emphasizes that modern divorce attorneys must fundamentally understand how digital assets are acquired, transferred, and stored.
Understanding the Mechanics of Blockchain Secrecy
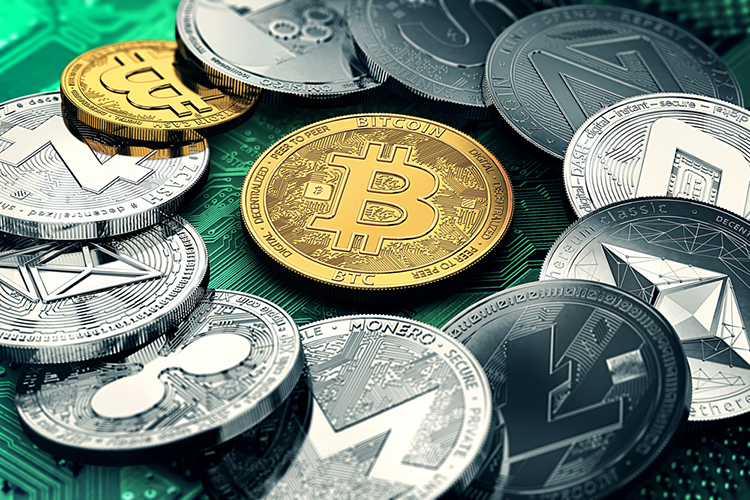
To comprehend why cryptocurrency presents such a daunting challenge in divorce litigation, one must understand the underlying technology. Unlike fiat currency managed by central banks and commercial institutions, cryptocurrencies operate on decentralized blockchain networks. Transactions occur directly between users without an intermediary bank clearinghouse.
Digital assets are typically secured in software or hardware wallets protected by cryptographic passkeys. Without the private key or seed phrase, accessing a wallet is virtually impossible for an outside party. This decentralized architecture creates a profound information asymmetry during divorce discovery. While traditional financial institutions are legally mandated to comply with subpoenas and produce historical account statements, discovering decentralized wallets often relies entirely on the voluntary cooperation of the spouse holding the assets—or the rigorous investigative work of forensic specialists.
Recognizing these vulnerabilities, certain jurisdictions have begun modernizing their legal procedures. In New York, for example, family court litigants must now complete updated statements of net worth that feature a dedicated section specifically for cryptocurrency assets. These reporting frameworks utilize targeted legal prompts designed to elicit explicit details regarding digital wallet addresses, exchange accounts, and historical transaction volumes.
Legal Strategies and Discovery Redesigns
Family law practitioners across the United States are completely revamping their discovery protocols to address the digital asset dilemma. Jennifer A. Brandt, chair of the family law group at Cozen O’Connor in Philadelphia and immediate past chair of the American Bar Association Section of Family Law, stresses that practitioners must proactively engage clients regarding the full spectrum of possible digital holdings.
Brandt advises attorneys to revise standard document requests to specifically capture digital wallet identifiers, hardware device locations, and accounts held on centralized and decentralized exchanges. "The most important thing is to be asking the right questions," Brandt notes, pointing out that general discovery requests targeting "bank accounts" are completely inadequate for uncovering digital wealth.
Furthermore, legal professionals face the daunting task of establishing equitable valuations. Unlike publicly traded equities or real estate appraised by comparable market sales, cryptocurrency valuations fluctuate wildly and lack traditional financial anchors, such as corporate earnings reports or underlying tangible assets. Determining whether an asset should be valued at the date of separation, the date of filing, or the date of trial can dramatically alter the financial outcome for both parties, yet there is currently very little settled court precedent guiding judges on how to divide digital tokens in the fairest manner possible.
Profiling Investors: Dabblers Versus Distrusters
In complex asset distribution cases, legal strategy often depends heavily on the psychological profile of the investor holding the digital currency. Karen M. Platt, a partner specializing in divorce litigation and asset distribution in the New York office of Pryor Cashman and chair-elect of the American Bar Association Family Law Section, categorizes crypto investors during divorce proceedings into two distinct archetypes: "dabblers" and "distrusters."
The dabbler, according to Platt, is the less complicated adversary in litigation. Dabblers typically hold modest amounts of cryptocurrency because the asset class is culturally prominent, because they are curious about blockchain technology, or simply because they want to project a modern image to their peers. Because dabblers generally purchase their digital assets through mainstream, regulated centralized exchanges—such as Coinbase, Kraken, or Gemini—their transaction histories are easily traceable. They are also significantly more inclined to produce requested account statements and cooperate with discovery orders.
Distrusters, however, present an entirely different legal challenge. Platt explains that individuals falling into the distruster category are drawn to cryptocurrency precisely because they harbor a deep skepticism toward traditional banking institutions, government oversight, and, frequently, their marital partners.
When a distruster manages marital wealth, the risk of asset dissipation skyrockets. These individuals are far more adept at transferring funds across multiple blockchain networks, utilizing decentralized finance (DeFi) protocols, privacy coins, or hardware wallets to obscure ownership. A determined distruster can successfully conceal hundreds of thousands—or even millions—of dollars behind complex cryptographic walls. In such cases, uncovering hidden wealth almost invariably requires retaining specialized forensic accountants to conduct exhaustive blockchain tracing operations.
The Economic Realities of Forensic Investigation
While forensic accountants and digital asset experts are indispensable tools in modern divorce litigation, their involvement introduces significant economic considerations. Victoria Fife, a forensic accountant and digital asset expert at CBIZ in Los Angeles who specializes in complex asset tracing and valuation for civil and family law litigation, emphasizes the necessity of early risk assessment.
Fife advises divorce lawyers to evaluate whether their clients have invested in crypto assets at the outset of representation. If meaningful digital holdings are identified, or if there is reasonable suspicion that a spouse has engaged in suspicious financial transfers, retaining a crypto forensic expert early in the proceedings is vital to prepare for sudden valuation disputes.
However, Fife issues a stern financial warning regarding the cost of these investigations. Deploying forensic accountants to trace cryptocurrency across public ledgers, untangle obfuscated transactions, and analyze cross-chain bridges can become "very, very, very costly." Because blockchain analysis requires specialized technical skills and intensive labor hours, legal fees can quickly spiral out of control, occasionally resulting in massive surprise expenses that outpace the value of the disputed assets.
For this reason, Fife recommends a pragmatic cost-benefit analysis before launching aggressive forensic audits. If legal counsel and their clients estimate that the contested cryptocurrency assets are worth less than $100,000, pursuing a comprehensive forensic investigation may be financially counterproductive. In such scenarios, exploring a negotiated settlement is often the wiser course of action, as the investigative and legal fees required to litigate the dispute could easily match or exceed the total value of the underlying digital portfolio.
Broader Implications and the Future of Family Law
The intersection of cryptocurrency and domestic relations law underscores a broader transformation within the global legal system. As technological innovation outpaces statutory development, courts and legislatures are forced to adapt reactive measures to protect equitable distribution rights.
The lack of unified federal or international standards regarding digital asset valuation and division creates jurisdictional disparities. State courts are left to interpret existing marital property statutes through the lens of decentralized ledgers, leading to inconsistent rulings across different courtrooms. Furthermore, the pseudonymous nature of blockchain transactions poses ongoing enforcement challenges for judges attempting to issue asset freeze orders or contempt citations against uncooperative litigants who control private keys stored overseas or memorized in seed phrases.
Ultimately, the rise of digital wealth in divorce proceedings signals the permanent end of traditional financial discovery. As blockchain technology becomes more deeply embedded in the global economy, family law attorneys can no longer view cryptocurrency as a passing trend or a secondary asset class. Successfully navigating the digital divide requires a multidisciplinary approach combining rigorous legal discovery, advanced technological literacy, and pragmatic financial evaluation to ensure that marital dissolutions remain equitable in an increasingly decentralized financial world.