JetBlue President Marty St. George Warns Airline Pricing Lacks Equilibrium Amid Escalating Operational Costs

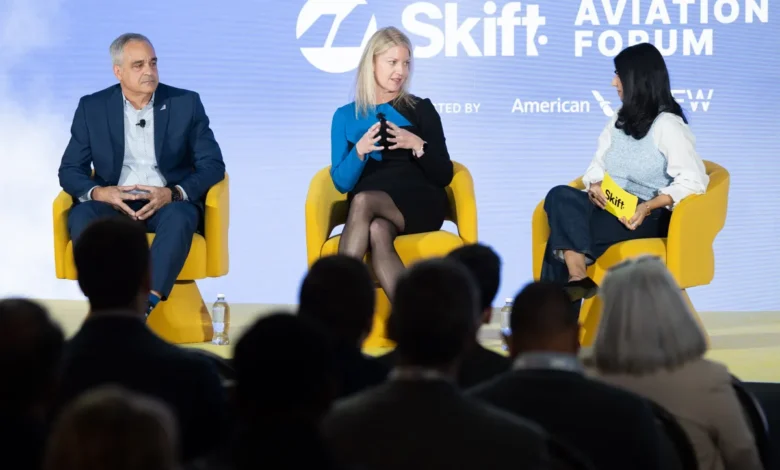
The ongoing post-pandemic evolution of commercial aviation continues to face significant financial headwinds as carriers grapple with persistent cost inflation and fluctuating consumer demand. Speaking ahead of a prominent industry appearance, JetBlue Airways President Marty St. George articulated a growing consensus among legacy and low-cost carriers alike: airline ticket pricing has yet to achieve a stable market equilibrium. This structural imbalance, driven largely by volatile jet fuel expenses, labor agreements, and supply chain constraints, underscores the complex economic realities shaping the aviation sector as executive leadership teams look toward operational planning for the coming years.
The timing of St. George’s remarks coincides with a pivotal gathering of aviation and commerce leaders in New York. On Wednesday, November 11, the JetBlue executive is scheduled to take the stage for a high-profile conversation with Brian Sumers, Editor of The Airline Observer. This keynote session serves a dual purpose within the industry event calendar, effectively closing out the Skift Commerce Summit while formally kicking off the Skift Aviation Forum 2026. The transition sets the stage for a subsequent gathering at the iconic TWA Hotel at John F. Kennedy International Airport, where top-tier airline executives will convene to finalize strategic network and financial plans for 2027.
Background Context of the Aviation Industry Events
The Skift Commerce Summit and the Skift Aviation Forum have established themselves as critical forums for dissecting the macroeconomic pressures influencing modern air travel. As airlines navigate the complex intersection of retail technology, distribution strategies, and yield management, events of this scale provide a transparent window into boardroom decision-making.
The aviation sector has undergone a profound transformation since the disruptions of the early 2020s. While passenger demand has largely rebounded to pre-pandemic volumes, the underlying cost structure of operating an airline has shifted dramatically. Inflationary pressures have touched nearly every aspect of the balance sheet, from aircraft maintenance and airport fees to pilot and flight attendant compensation packages secured through recent collective bargaining agreements. Consequently, airline revenue management teams are perpetually tasked with recalibrating pricing algorithms to protect profit margins without stifling passenger volume.
Chronology of Modern Airline Pricing Pressures
To understand the current state of airline economics, it is necessary to examine the chronological progression of market shocks that have defined the decade.
In the immediate wake of global travel restrictions lifting in 2021 and 2022, the industry experienced a phenomenon widely described as revenge travel. Consumers, sitting on accumulated savings and eager to fly, absorbed rapid fare increases without significant resistance. Airlines posted robust top-line revenues, temporarily masking structural cost increases.
By 2023, however, the macroeconomic landscape shifted. Pent-up demand began to normalize, giving way to a more price-sensitive consumer base. Simultaneously, global supply chain bottlenecks delayed aircraft deliveries from major manufacturers like Boeing and Airbus, forcing carriers to keep older, less fuel-efficient planes in service longer than anticipated. This constraint on capacity growth coincided with unpredictable spikes in crude oil prices, which directly impacted jet fuel—consistently one of the largest variable expenses for any airline.
Entering 2024 and looking ahead to the planning cycles for 2026 and 2027, carriers found themselves trapped between rising baseline operational expenses and heightened fare transparency driven by digital comparison tools and regulatory scrutiny regarding ancillary fees. St. George’s observation that pricing lacks equilibrium directly reflects this multi-year squeeze, where traditional pricing models struggle to keep pace with a permanently elevated cost baseline.
Supporting Data and Market Metrics
The financial metrics underpinning St. George’s analysis illustrate the severity of the operational challenges facing domestic and international carriers. According to data from the International Air Transport Association (IATA) and the U.S. Department of Transportation, jet fuel prices have stabilized below their historic 2022 peaks but remain substantially higher and more volatile than the averages recorded throughout the 2010s. Fuel routinely accounts for between 25% and 30% of an airline’s total operating expenses, depending on hedging strategies and fleet efficiency.
Concurrently, labor costs have surged. Major U.S. carriers, including Delta Air Lines, United Airlines, American Airlines, and Southwest Airlines, have ratified landmark contracts yielding cumulative pay increases ranging from 30% to 40% over the life of the agreements. As a baseline competitor in the low-cost and leisure-heavy segments, JetBlue has similarly had to adapt its compensation structures to retain critical talent amid industry-wide shortages of pilots and certified mechanics.
Furthermore, capacity deployment has failed to match historical linear growth models. Delays in aircraft certifications and manufacturing output have restricted the number of available seats in the marketplace. While constrained capacity theoretically supports higher ticket prices, the elasticity of demand has created a ceiling. Leisure travelers, in particular, have demonstrated increased resistance to premium economy and main cabin fares as broader economic uncertainty influences household budgets.
Official Responses and Industry Perspectives
Reactions from across the aviation sector reflect a shared anxiety regarding yield management and margin sustainability. While network legacy carriers have leaned heavily into premium seating cabins—such as business class and premium economy—to offset rising costs, low-cost carriers like JetBlue face a more delicate balancing act.
Commercial and revenue leaders within these organizations are forced to ask a fundamental question: exactly how much of the escalating fuel and labor bill can passenger fares realistically carry?
During industry briefings and earnings calls throughout the year, executives from various carriers have echoed the sentiment that the era of ultra-low baseline fares may be permanently receding. Competitors note that while promotional sales continue to stimulate demand during off-peak periods, the underlying cost of maintaining safe, reliable, and punctual operations requires a higher yield per passenger mile.
Moreover, airline executives have increasingly pointed to ancillary revenues—baggage fees, seat selection charges, and loyalty program monetization—as vital shock absorbers. However, regulatory pressures from transportation authorities regarding fee transparency and consumer protections have complicated reliance on these secondary revenue streams, forcing airlines to refocus on core ticket pricing equilibrium.
Broader Impact and Implications for 2027 Planning
The discussions taking place at the TWA Hotel during the upcoming Skift forums carry profound implications for travelers, investors, and industry regulators alike. As leadership teams finalize their operational blueprints for 2027, several strategic imperatives emerge from the current pricing disequilibrium.
First, capacity discipline is expected to remain the dominant strategy. Rather than engaging in aggressive market-share expansion that historically led to fare wars and compressed margins, airlines are increasingly prioritizing yield over volume. This disciplined approach means that flight schedules may remain tightly managed, potentially resulting in fewer flights on secondary routes and higher average ticket prices for consumers during peak travel windows.
Second, technological innovation in revenue management will play a decisive role. Airlines are heavily investing in artificial intelligence and machine learning tools capable of processing real-time market signals, competitor pricing, and hyper-local demand fluctuations. These advanced systems aim to help commercial leaders navigate the elusive equilibrium St. George referenced, ensuring that fares dynamically adjust to absorb cost spikes without alienating price-sensitive flyers.
Finally, the broader economic health of the aviation sector remains inextricably linked to broader macroeconomic trends. As central banks manage interest rates and consumer confidence indexes fluctuate, the airline industry serves as an immediate barometer of economic vitality. The ability of carriers like JetBlue to successfully recalibrate their pricing structures will determine not only their individual profitability but also the future accessibility and affordability of commercial air travel for the flying public.