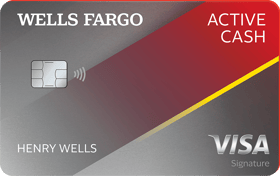
Why the Wells Fargo Active Cash Card Dominates the 2026 Credit Card Landscape Through Unmatched Flat-Rate Rewards and Zero Annual Fees

The modern personal finance landscape continues to evolve rapidly, placing immense pressure on consumers to optimize their everyday spending. In this competitive ecosystem, finding a credit card that balances simplicity, high-yield cash back, and zero overhead costs can be a daunting task. However, financial analysts and consumer advocates have increasingly pointed to a standout product leading the sector: the Wells Fargo Active Cash Card. Crowned as the Best Credit Card for 2026 by leading industry experts, this financial instrument has captured significant market share by offering a streamlined approach to rewards without sacrificing long-term value.
The Evolution of Flat-Rate Cash Back in Personal Finance
For decades, credit card issuers relied heavily on rotating bonus categories, requiring cardholders to track complex calendar quarters, activate perks manually, and navigate spending caps. While these niche rewards cards can yield high returns for meticulous budgeters, they often alienate consumers seeking a reliable, low-maintenance financial tool. The introduction of flat-rate cash back cards revolutionized the industry by offering a single, consistent percentage back on every purchase, regardless of the merchant category.
The Wells Fargo Active Cash Card entered this competitive arena with a clear objective: eliminate friction for the consumer. By offering an unlimited 2% cash rewards structure on all purchases, the card removes the need for mental arithmetic or category tracking. Industry analysts note that this shift toward universal, flat-rate rewards reflects changing consumer preferences toward convenience, predictability, and immediate financial transparency.
Core Features and Value Proposition of the Wells Fargo Active Cash Card
A comprehensive review of the card’s financial mechanics reveals why it has secured top honors for 2026. Designed for applicants with good to excellent credit scores typically ranging from 670 to 850, the card bridges the gap between premium travel rewards programs and basic cash-back instruments.

Unlimited 2% Cash Rewards
The primary driver of the card’s popularity is its unlimited 2% cash rewards rate. Unlike competitors that cap high-tier earnings after a certain expenditure threshold or restrict elevated rewards to specific merchant types, the Active Cash Card applies its 2% rate universally. Whether a cardholder is purchasing groceries, paying utility bills, or booking unexpected emergency repairs, every dollar spent contributes equally to their cash-back balance. This consistency makes it an ideal cornerstone for any consumer wallet, particularly for expenses that traditionally fall outside bonus categories.
Competitive Welcome Offer
Sign-up bonuses are a staple of the credit card industry, but they are rarely attached to unlimited 2% cash-back products. New cardholders can earn a $100 cash rewards bonus after spending $500 in purchases within the first three months of account opening. Financial experts emphasize that this low spending threshold is exceptionally achievable for the average consumer, contrasting sharply with premium rewards cards that require thousands of dollars in spending over similar timeframes to unlock introductory bonuses.
Introductory and Standard APR Structure
Financial flexibility is another critical component of the card’s appeal. New applicants benefit from a 0% introductory APR for 12 months from account opening on both purchases and qualifying balance transfers. This feature provides a valuable financial buffer for individuals looking to finance major upcoming purchases or consolidate high-interest debt from legacy credit accounts. Following the conclusion of the 12-month promotional window, a variable regular APR of 18.74%, 24.74%, or 28.74% applies, depending on creditworthiness and prevailing market rates.
Zero Annual Fee
Perhaps most importantly for budget-conscious consumers, the card carries an annual fee of $0. In an economic environment where cardholders are increasingly auditing their recurring subscriptions and membership costs, avoiding an annual fee ensures that every dollar earned through cash back represents pure, unmitigated profit.
Built-in Cell Phone Protection
Beyond standard financial rewards, the Wells Fargo Active Cash Card offers tangible consumer protections that add significant, often overlooked value. Cardholders who pay their monthly cellular telephone bill using the card receive up to $600 in cell phone protection against damage or theft, subject to a nominal $25 deductible. Given the rising cost of modern smartphones—frequently exceeding hundreds or even thousands of dollars—this built-in insurance policy provides peace of mind that rivals dedicated standalone mobile device plans.
Comparative Market Analysis: Where It Stands Against Competitors
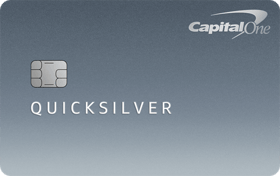
To fully understand the market dominance of the Wells Fargo Active Cash Card, financial researchers routinely benchmark it against other industry titans, such as the Capital One Quicksilver Cash Rewards Credit Card and the Citi Double Cash Card.
The Capital One Quicksilver offers a 1.5% flat cash-back rate on all purchases, paired with a slightly larger $200 welcome bonus after spending $500 in the first three months and a 15-month introductory 0% APR period on purchases and balance transfers. While the extended introductory window and higher sign-up bonus appeal to certain consumers, the lower permanent cash-back rate (1.5% compared to Wells Fargo’s 2%) means heavy spenders will accumulate rewards at a slower pace over the life of the card.
Similarly, the Citi Double Cash Card utilizes a unique rewards structure that yields effectively 2% back—1% at the time of purchase and an additional 1% when paying off the balance. While the ultimate earning potential matches the Wells Fargo Active Cash Card, the two-tier redemption requirement can introduce tracking complexities for users who prefer immediate, frictionless rewards allocation. Furthermore, the Active Cash Card distinguishes itself by combining its flat 2% rewards rate with both an upfront cash sign-up bonus and cell phone protection, creating a more comprehensive holistic package.
Strategic Considerations for Prospective Applicants
Financial advisors emphasize that while rewards cards offer substantial monetary benefits, they require disciplined management to maximize utility. Consumers evaluating the Wells Fargo Active Cash Card should consider several strategic factors:
- Credit Score Threshold: While pre-qualification tools allow consumers to check potential approval odds without harming their credit score, formal approval generally necessitates a credit score in the "good to excellent" range (670 to 850). Individuals actively rebuilding their credit profiles may need to explore specialized secured card options before applying.
- Payment Discipline: The lucrative rewards and 0% intro APR offers lose their financial efficacy if a cardholder carries a balance past the 12-month promotional period, as standard variable APRs can quickly offset cash-back gains. Maintaining a practice of paying balances in full each month remains paramount.
- Displacement of Debit Cards: For consumers still relying primarily on traditional bank debit cards for daily transactions, transitioning to a product like the Active Cash Card offers a dual advantage. Beyond earning a 2% return on routine spending, credit cards provide superior federal fraud protections under the Fair Credit Billing Act compared to standard debit instruments tied directly to checking accounts.
Broader Economic Implications and Industry Trends
The sustained popularity of flat-rate 2% cash-back cards highlights a broader maturation within the consumer credit sector. As digital banking platforms streamline reward redemptions and consumers demand greater transparency, issuers face mounting pressure to deliver straightforward, high-value products. Complex point systems and tiered travel portals, while lucrative for frequent flyers and luxury travelers, increasingly share market space with utilitarian cash-back instruments designed for the everyday economy.
Furthermore, the integration of ancillary perks—such as cell phone insurance—into no-annual-fee cards reflects an increasingly competitive battleground for primary wallet status. Issuers recognize that capturing a consumer’s daily transactional volume requires offering more than just a high percentage back; it requires building a resilient financial safety net around the cardholder’s routine expenses.
Conclusion: Making the Right Choice for Your Wallet
The designation of the Wells Fargo Active Cash Card as the Best Credit Card for 2026 underscores a shift toward efficiency, simplicity, and reliable consumer value. By pairing an unlimited 2% cash rewards rate with an achievable welcome bonus, a 12-month 0% introductory APR window, zero annual fees, and built-in mobile device protection, the card delivers a remarkably comprehensive package for a wide demographic of spenders.
For consumers seeking to maximize their purchasing power without navigating complicated reward tiers or absorbing recurring maintenance fees, the Active Cash Card remains a formidable benchmark in modern personal finance. As economic conditions continue to fluctuate, financial tools that prioritize clear, uncompromised value will undoubtedly remain essential components of a sound, resilient household budget.
Related posts: