Strategic Credit Card Management: A Comprehensive Guide to Optimizing Rewards and Travel Benefits

The modern consumer landscape is increasingly defined by a complex ecosystem of credit card rewards, where the strategic allocation of spending can result in significant financial gains or, conversely, wasted potential. While many individuals maintain a large portfolio of credit cards, the true value of these financial products is rarely found in the sheer number of accounts held. Instead, value is derived from a clear, tiered understanding of how specific cards function within a broader fiscal framework. Experts generally categorize these cards into three distinct buckets: cards held for their recurring benefits, cards utilized for specialized spending categories, and cards used as general "catch-all" instruments for everyday expenses.
A professional approach to credit card management requires distinguishing between the convenience of payment processing and the tactical maximization of points, miles, and cash-back returns. By analyzing the current market offerings from major issuers—including Citibank, American Express, Chase, and Capital One—one can construct a wallet strategy that balances annual fees against tangible returns in the form of travel credits, lounge access, and high-multiplier earning potential.
The Evolution of the High-End Travel Card Market
The competitive landscape for premium credit cards has shifted dramatically over the past decade. Financial institutions have moved away from basic point-earning structures toward integrated lifestyle benefits. This shift is most visible in the proliferation of branded airport lounges and specialized travel credits.
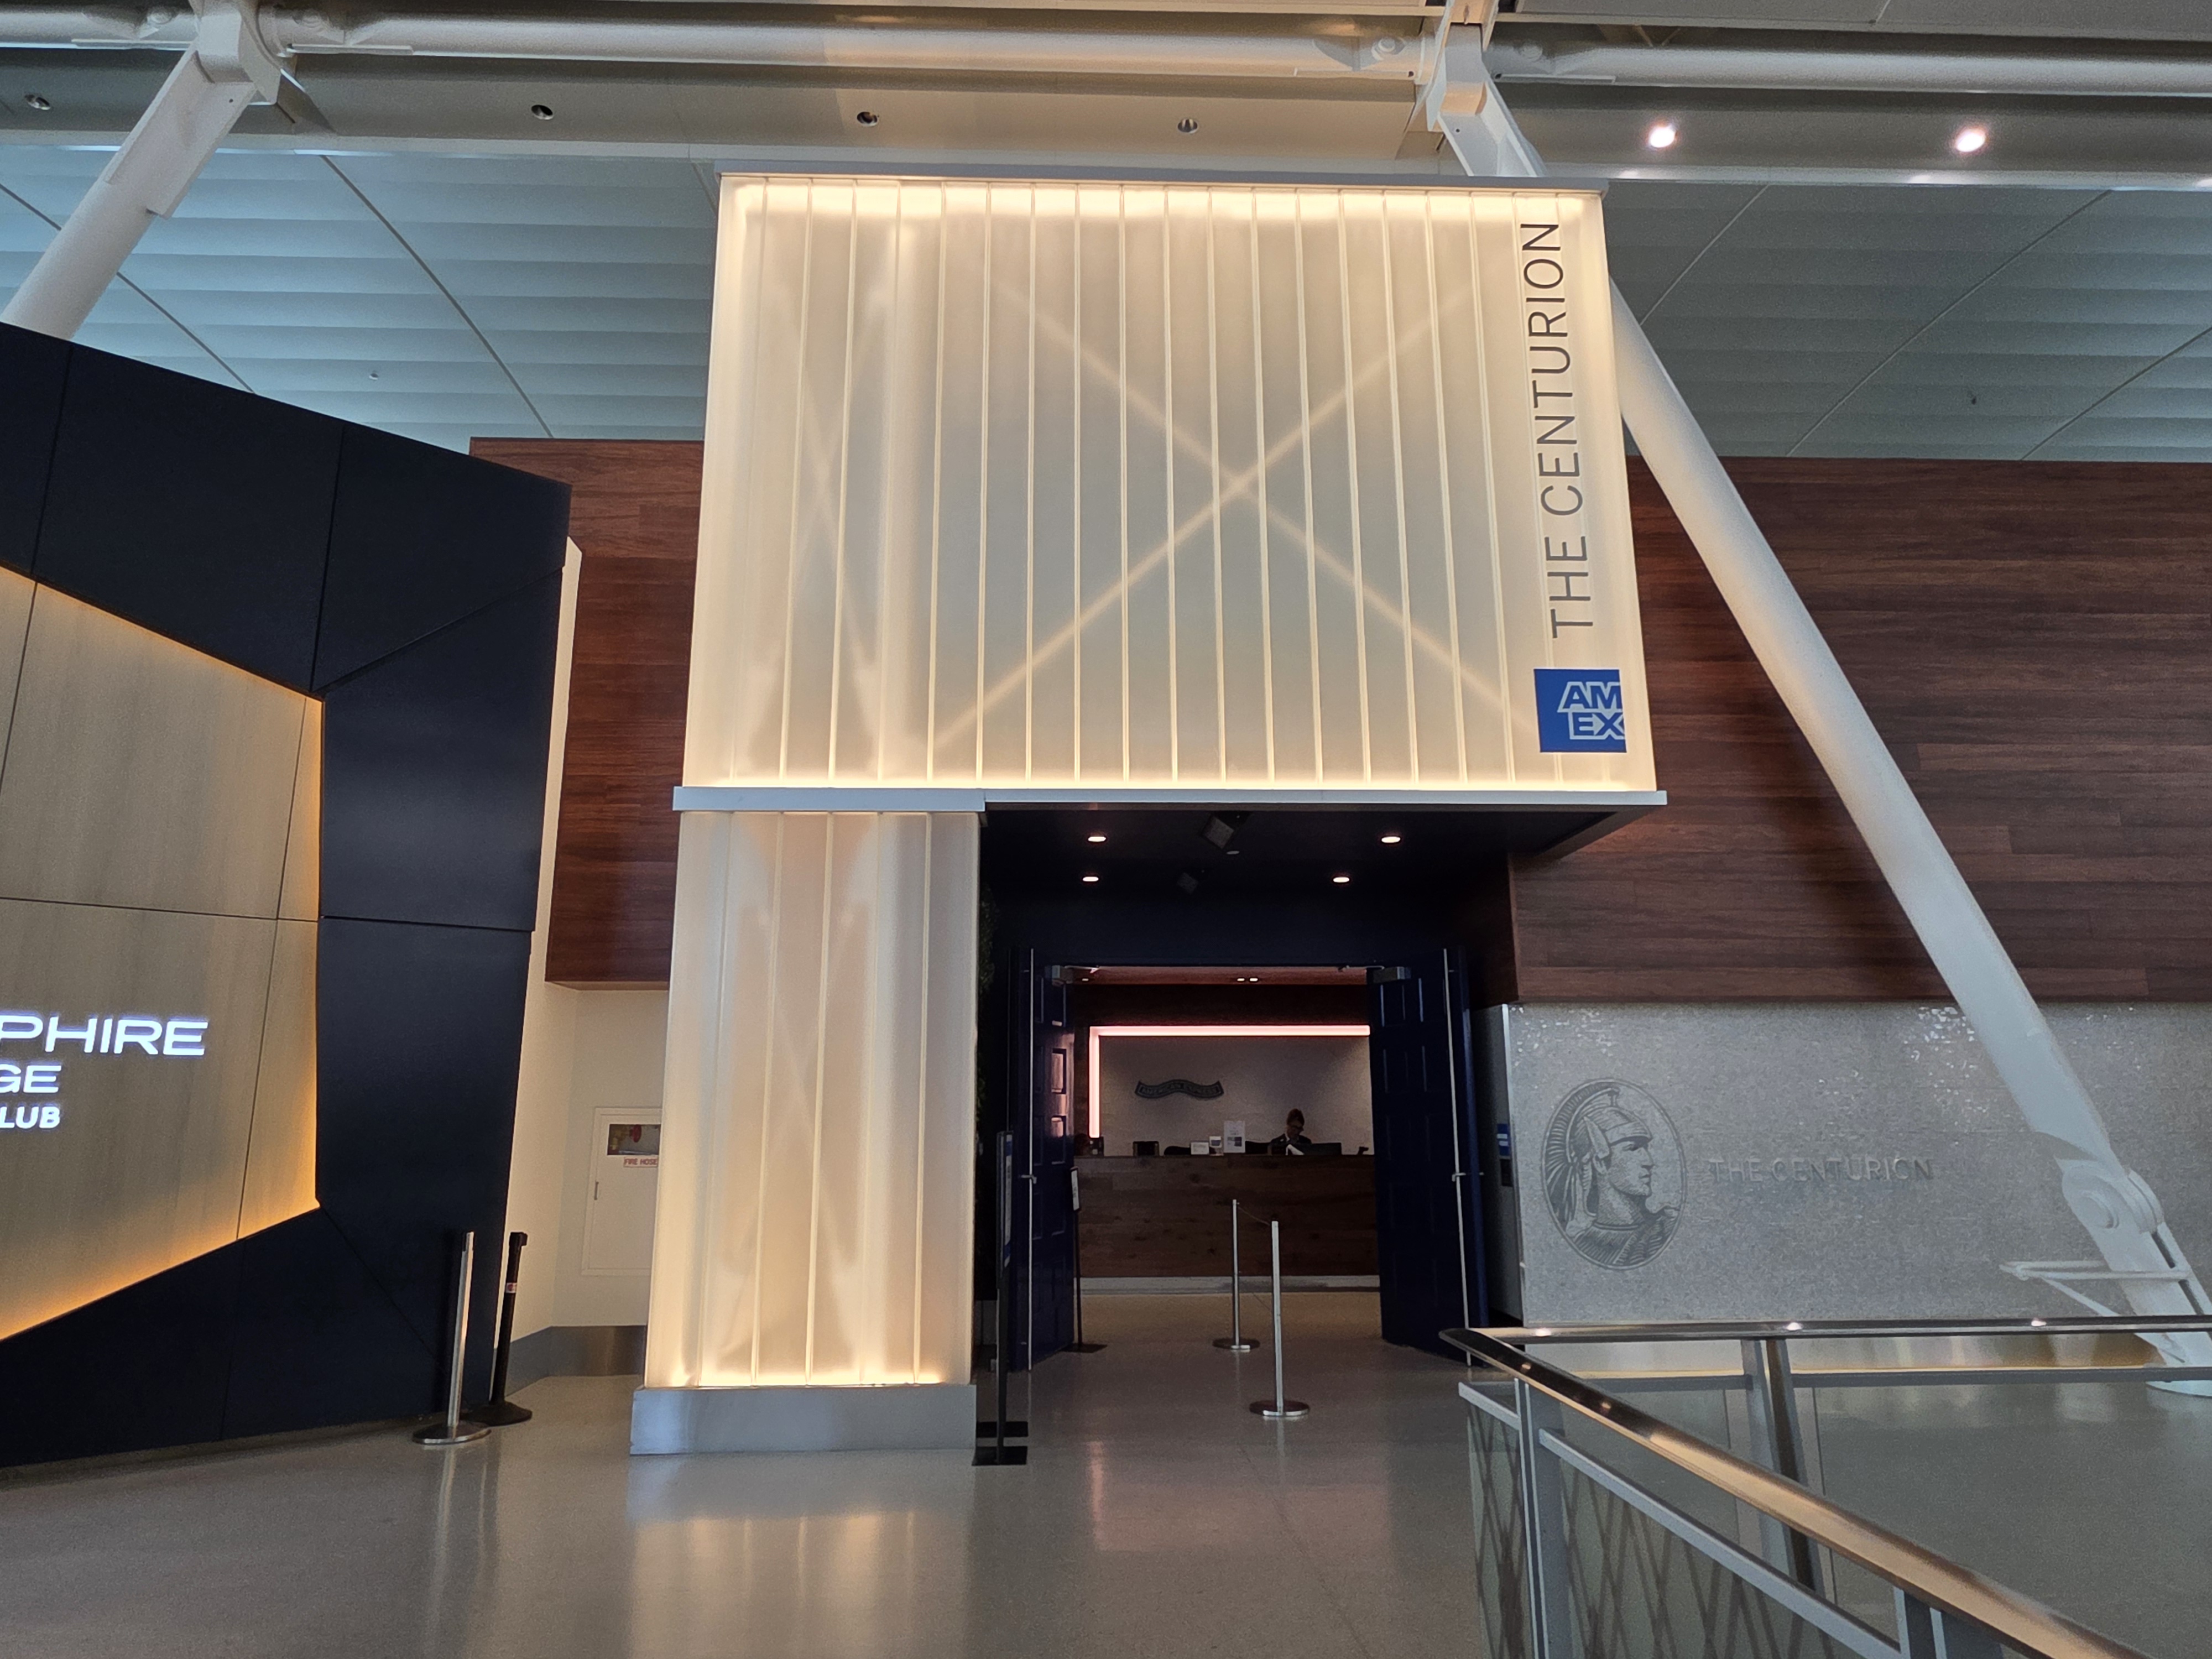
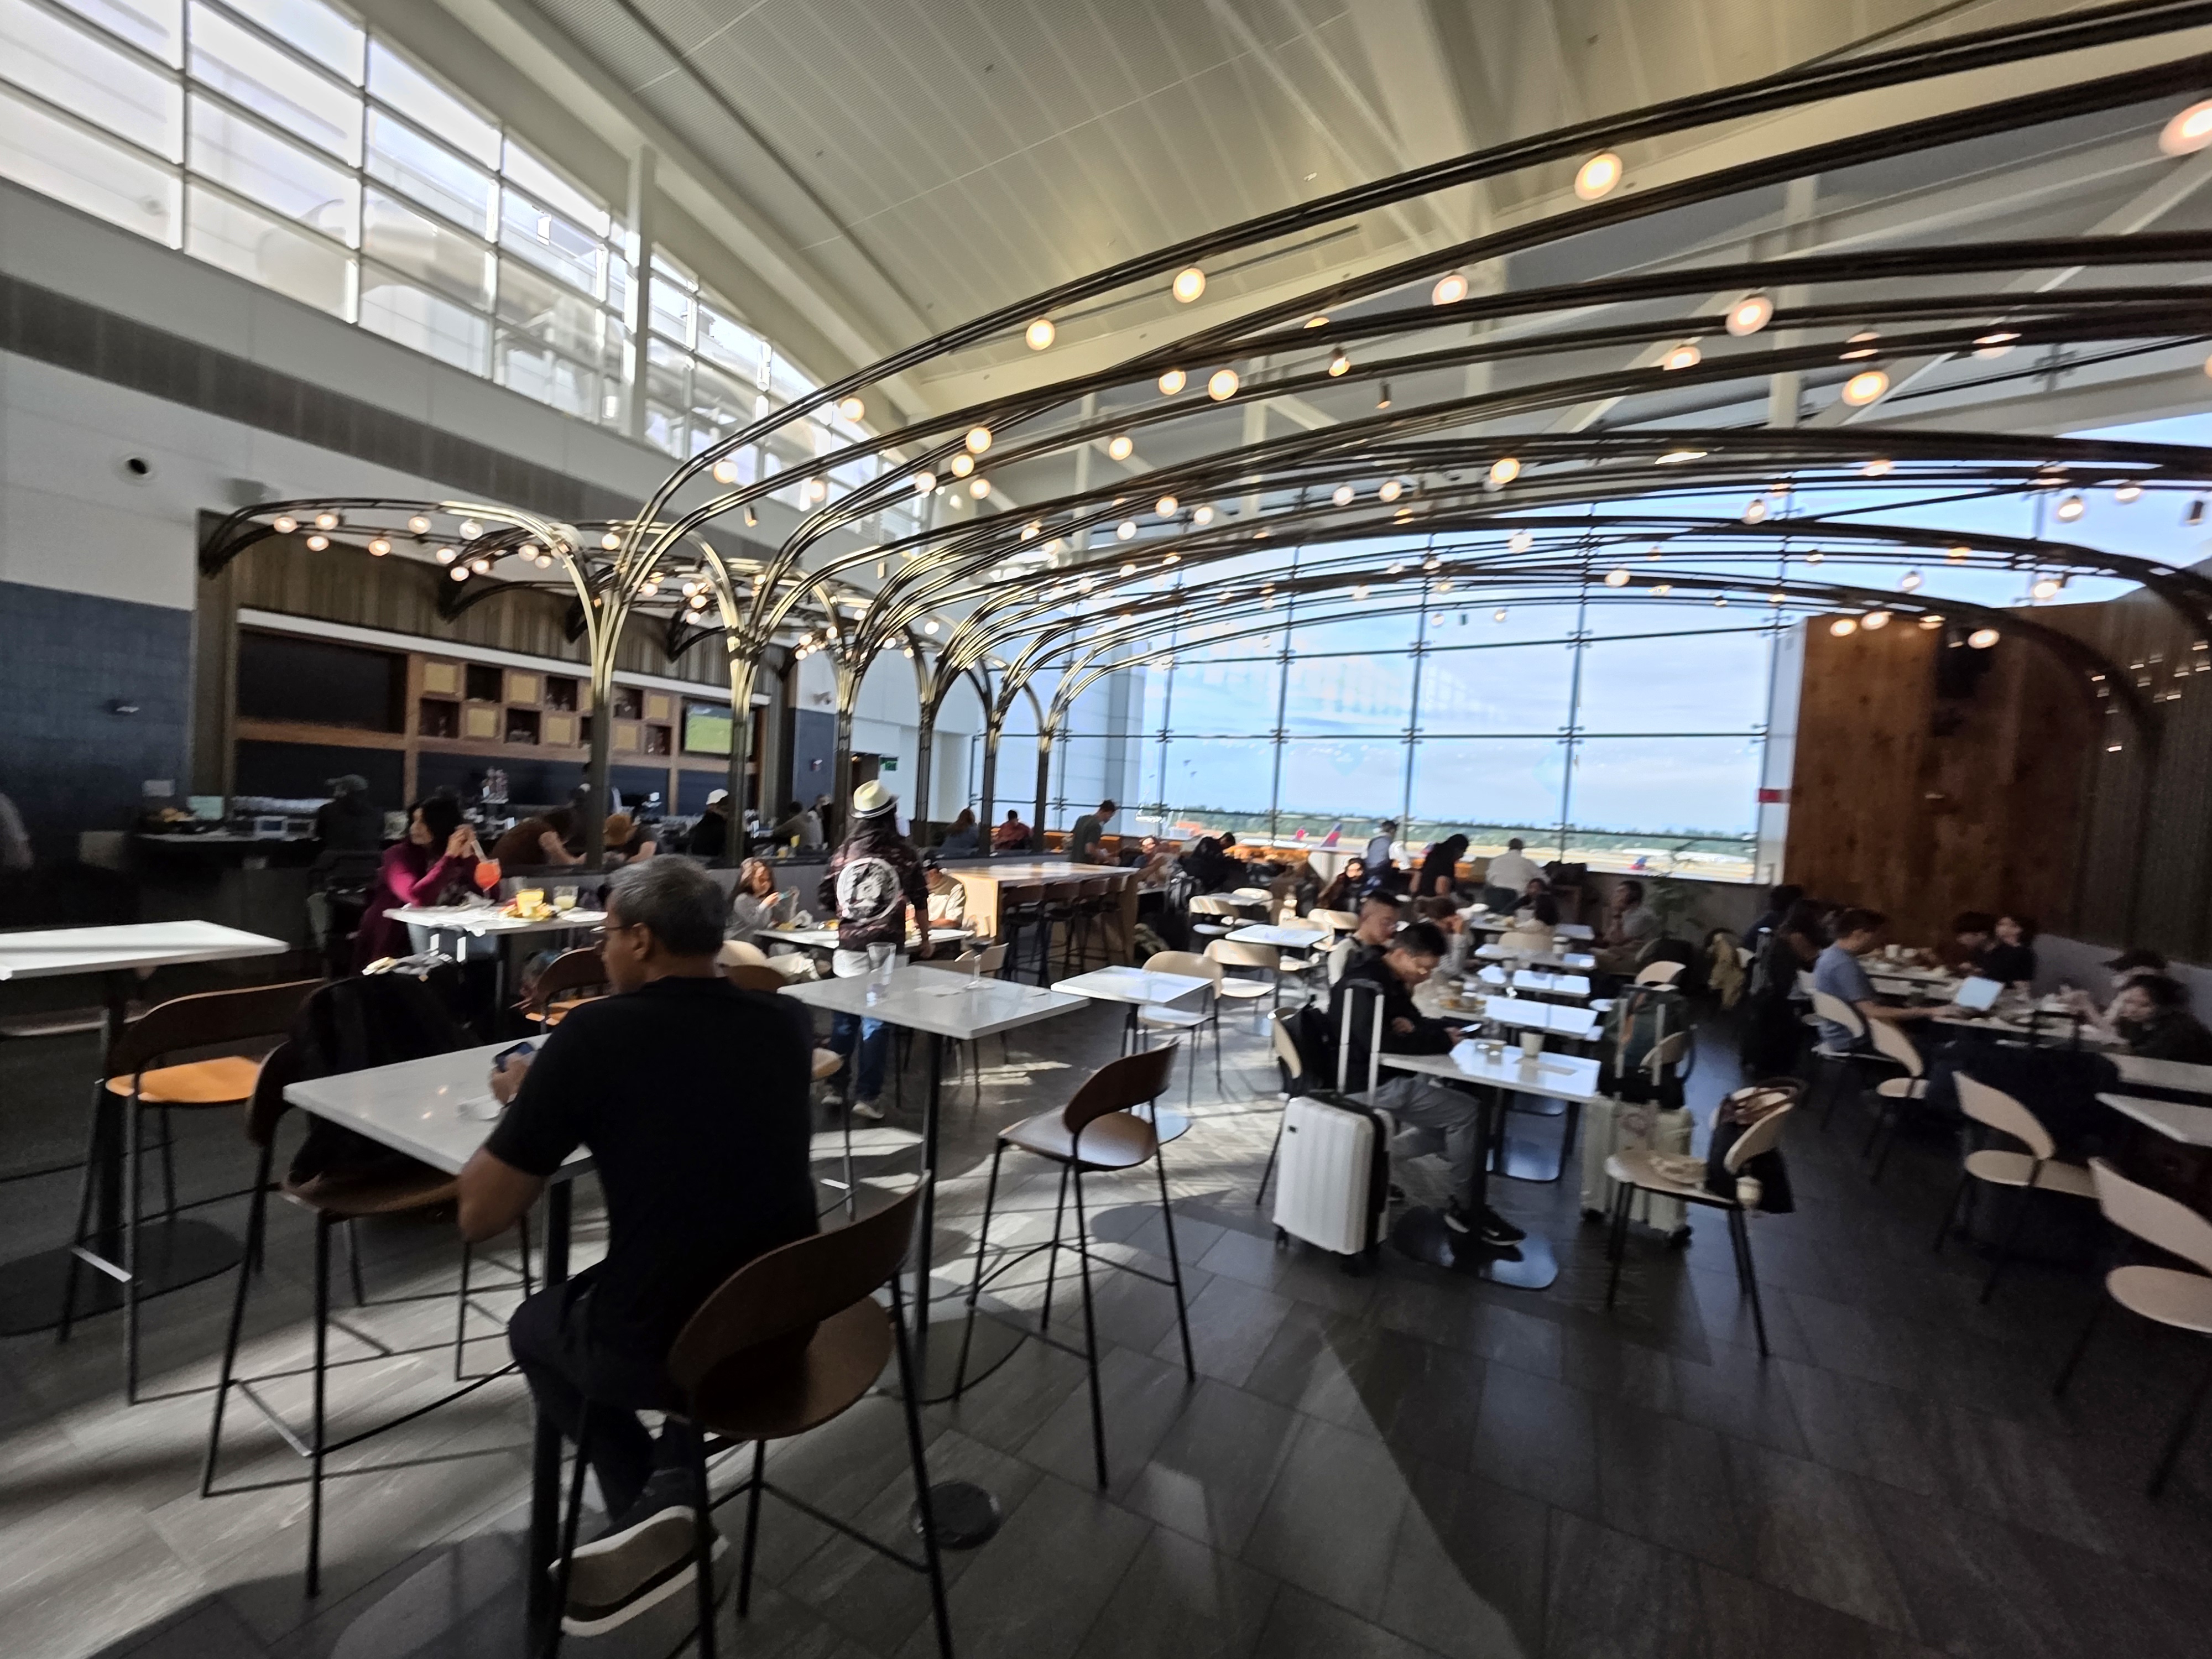
Chase, for instance, has significantly expanded its footprint with the Sapphire Lounge network. Locations in Boston, New York (JFK and LaGuardia), Las Vegas, Philadelphia, Phoenix, San Diego, and Washington Dulles demonstrate a commitment to elevating the airport experience. These lounges are designed to provide amenities that surpass standard Priority Pass offerings, often including bespoke dining and dedicated relaxation spaces. The inclusion of Priority Pass Select membership remains a standard for premium cards, providing access to over 1,300 global lounges.
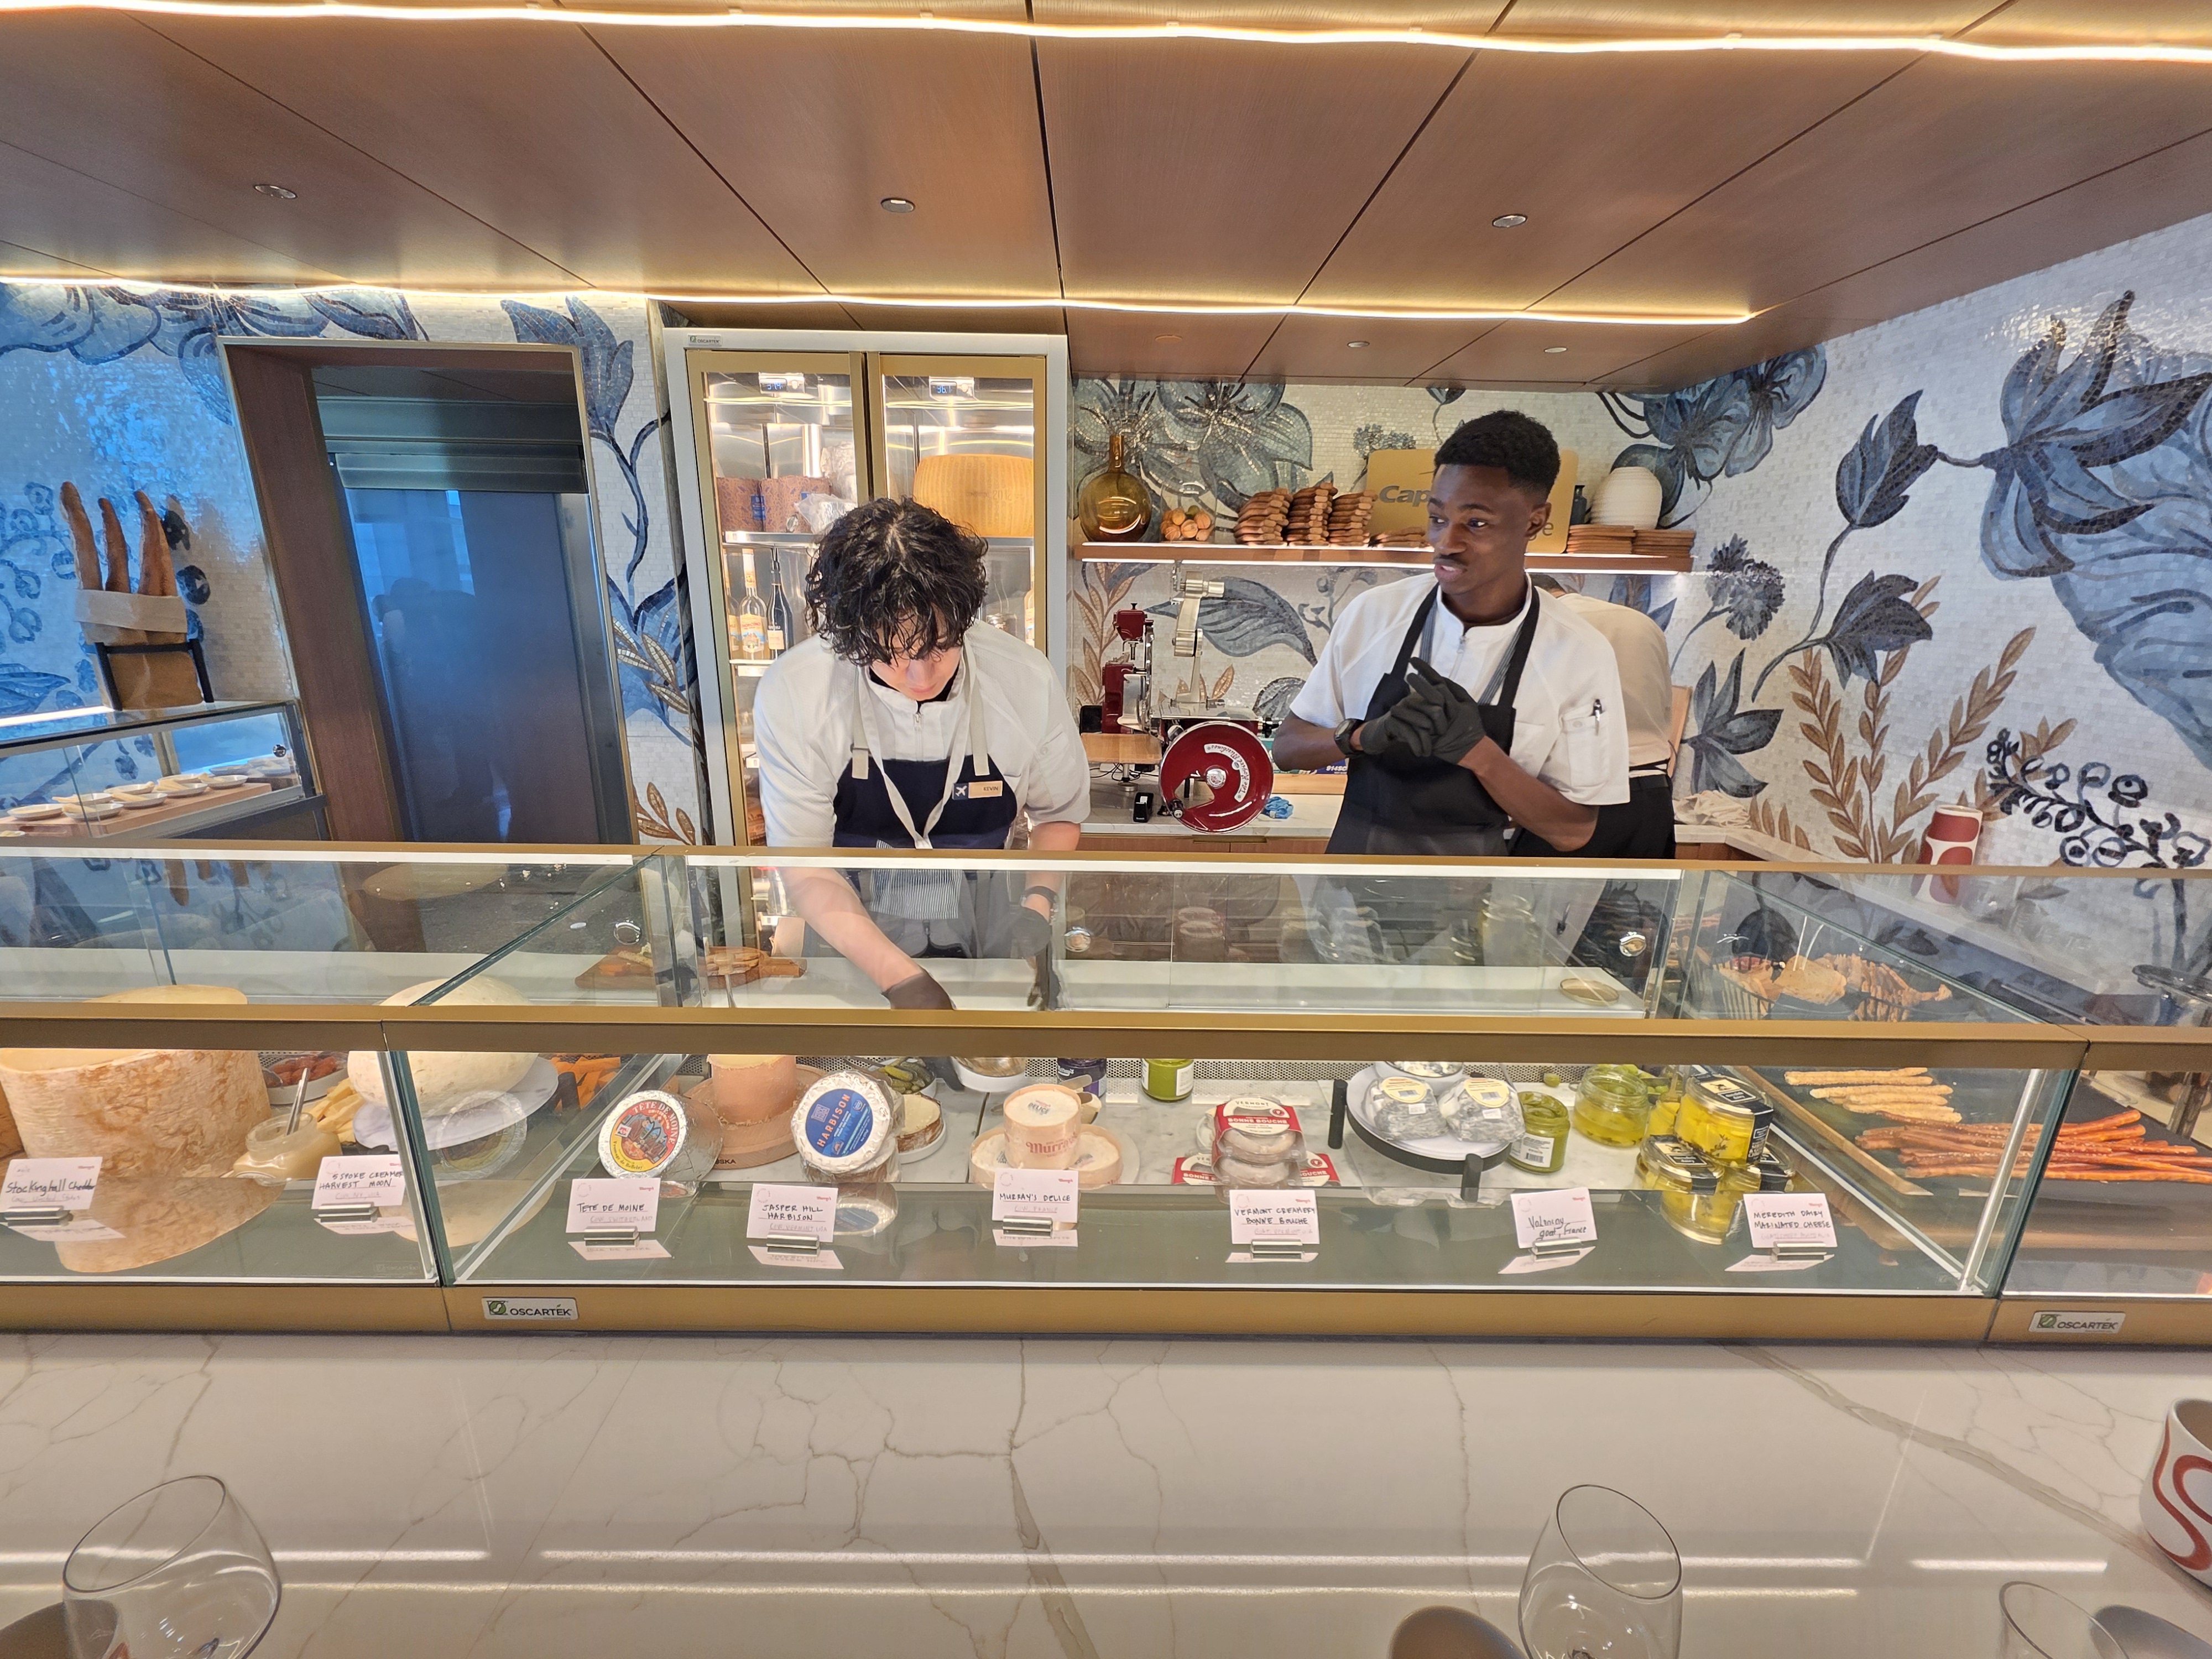
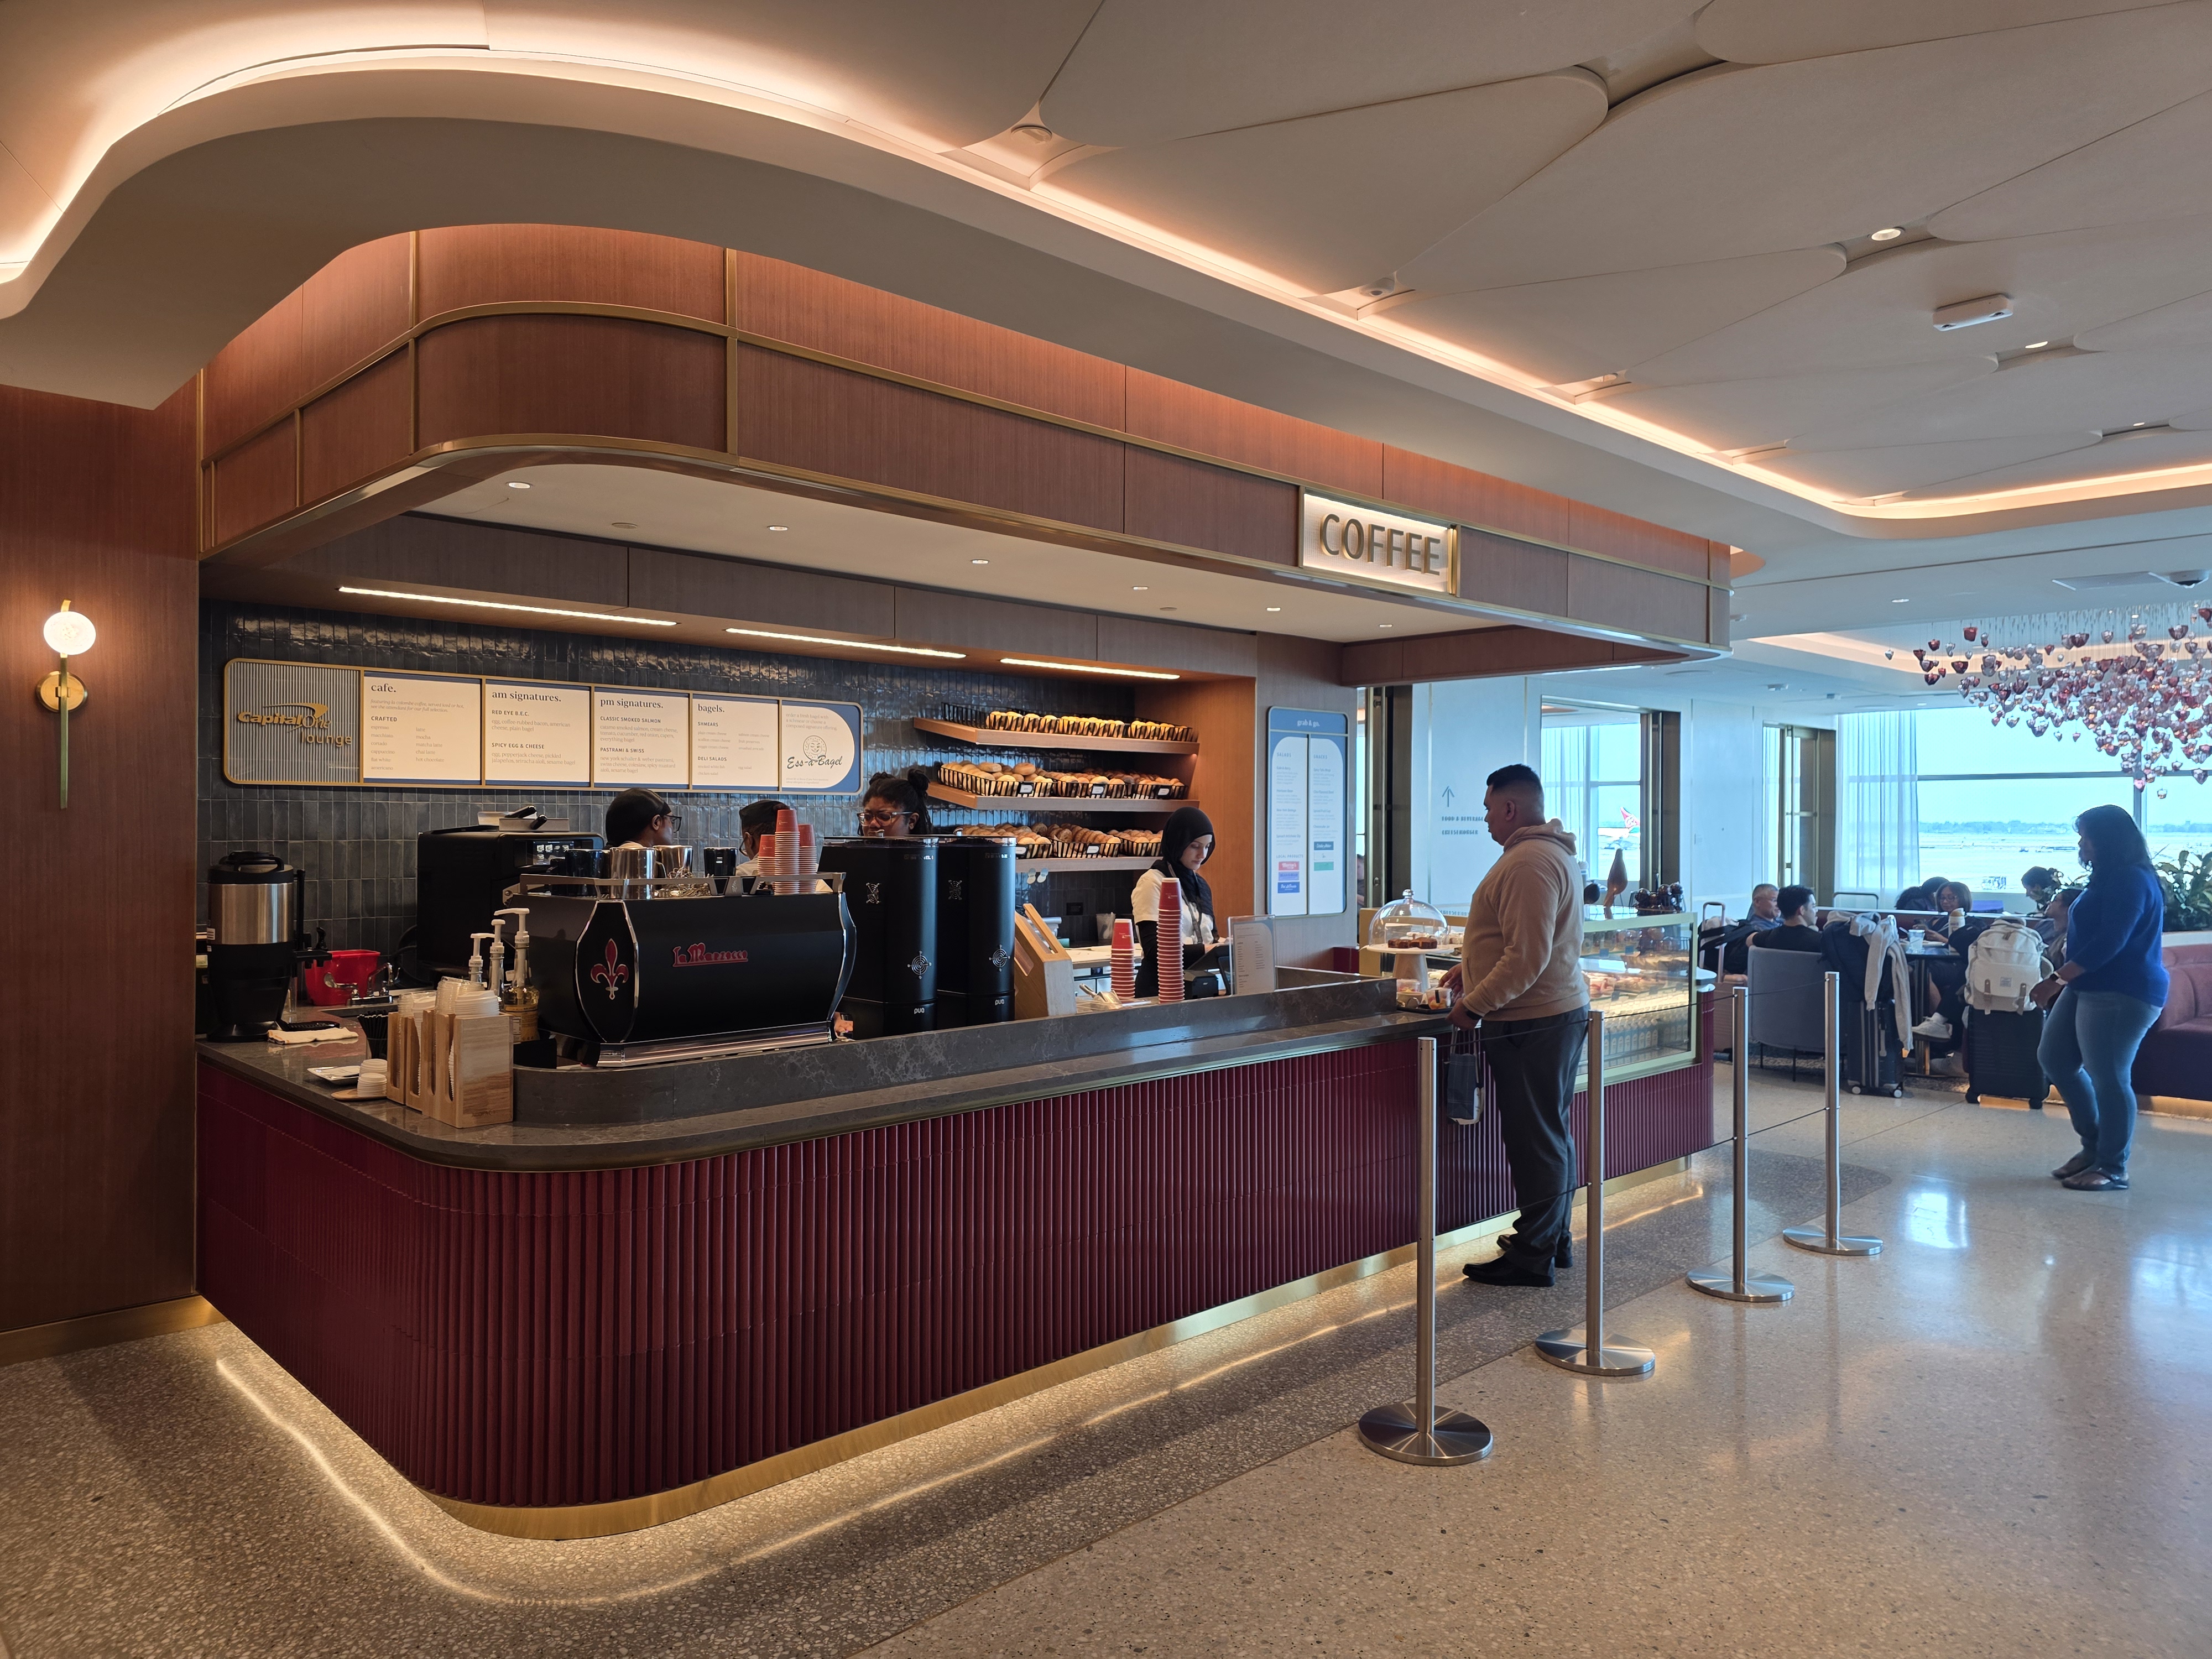
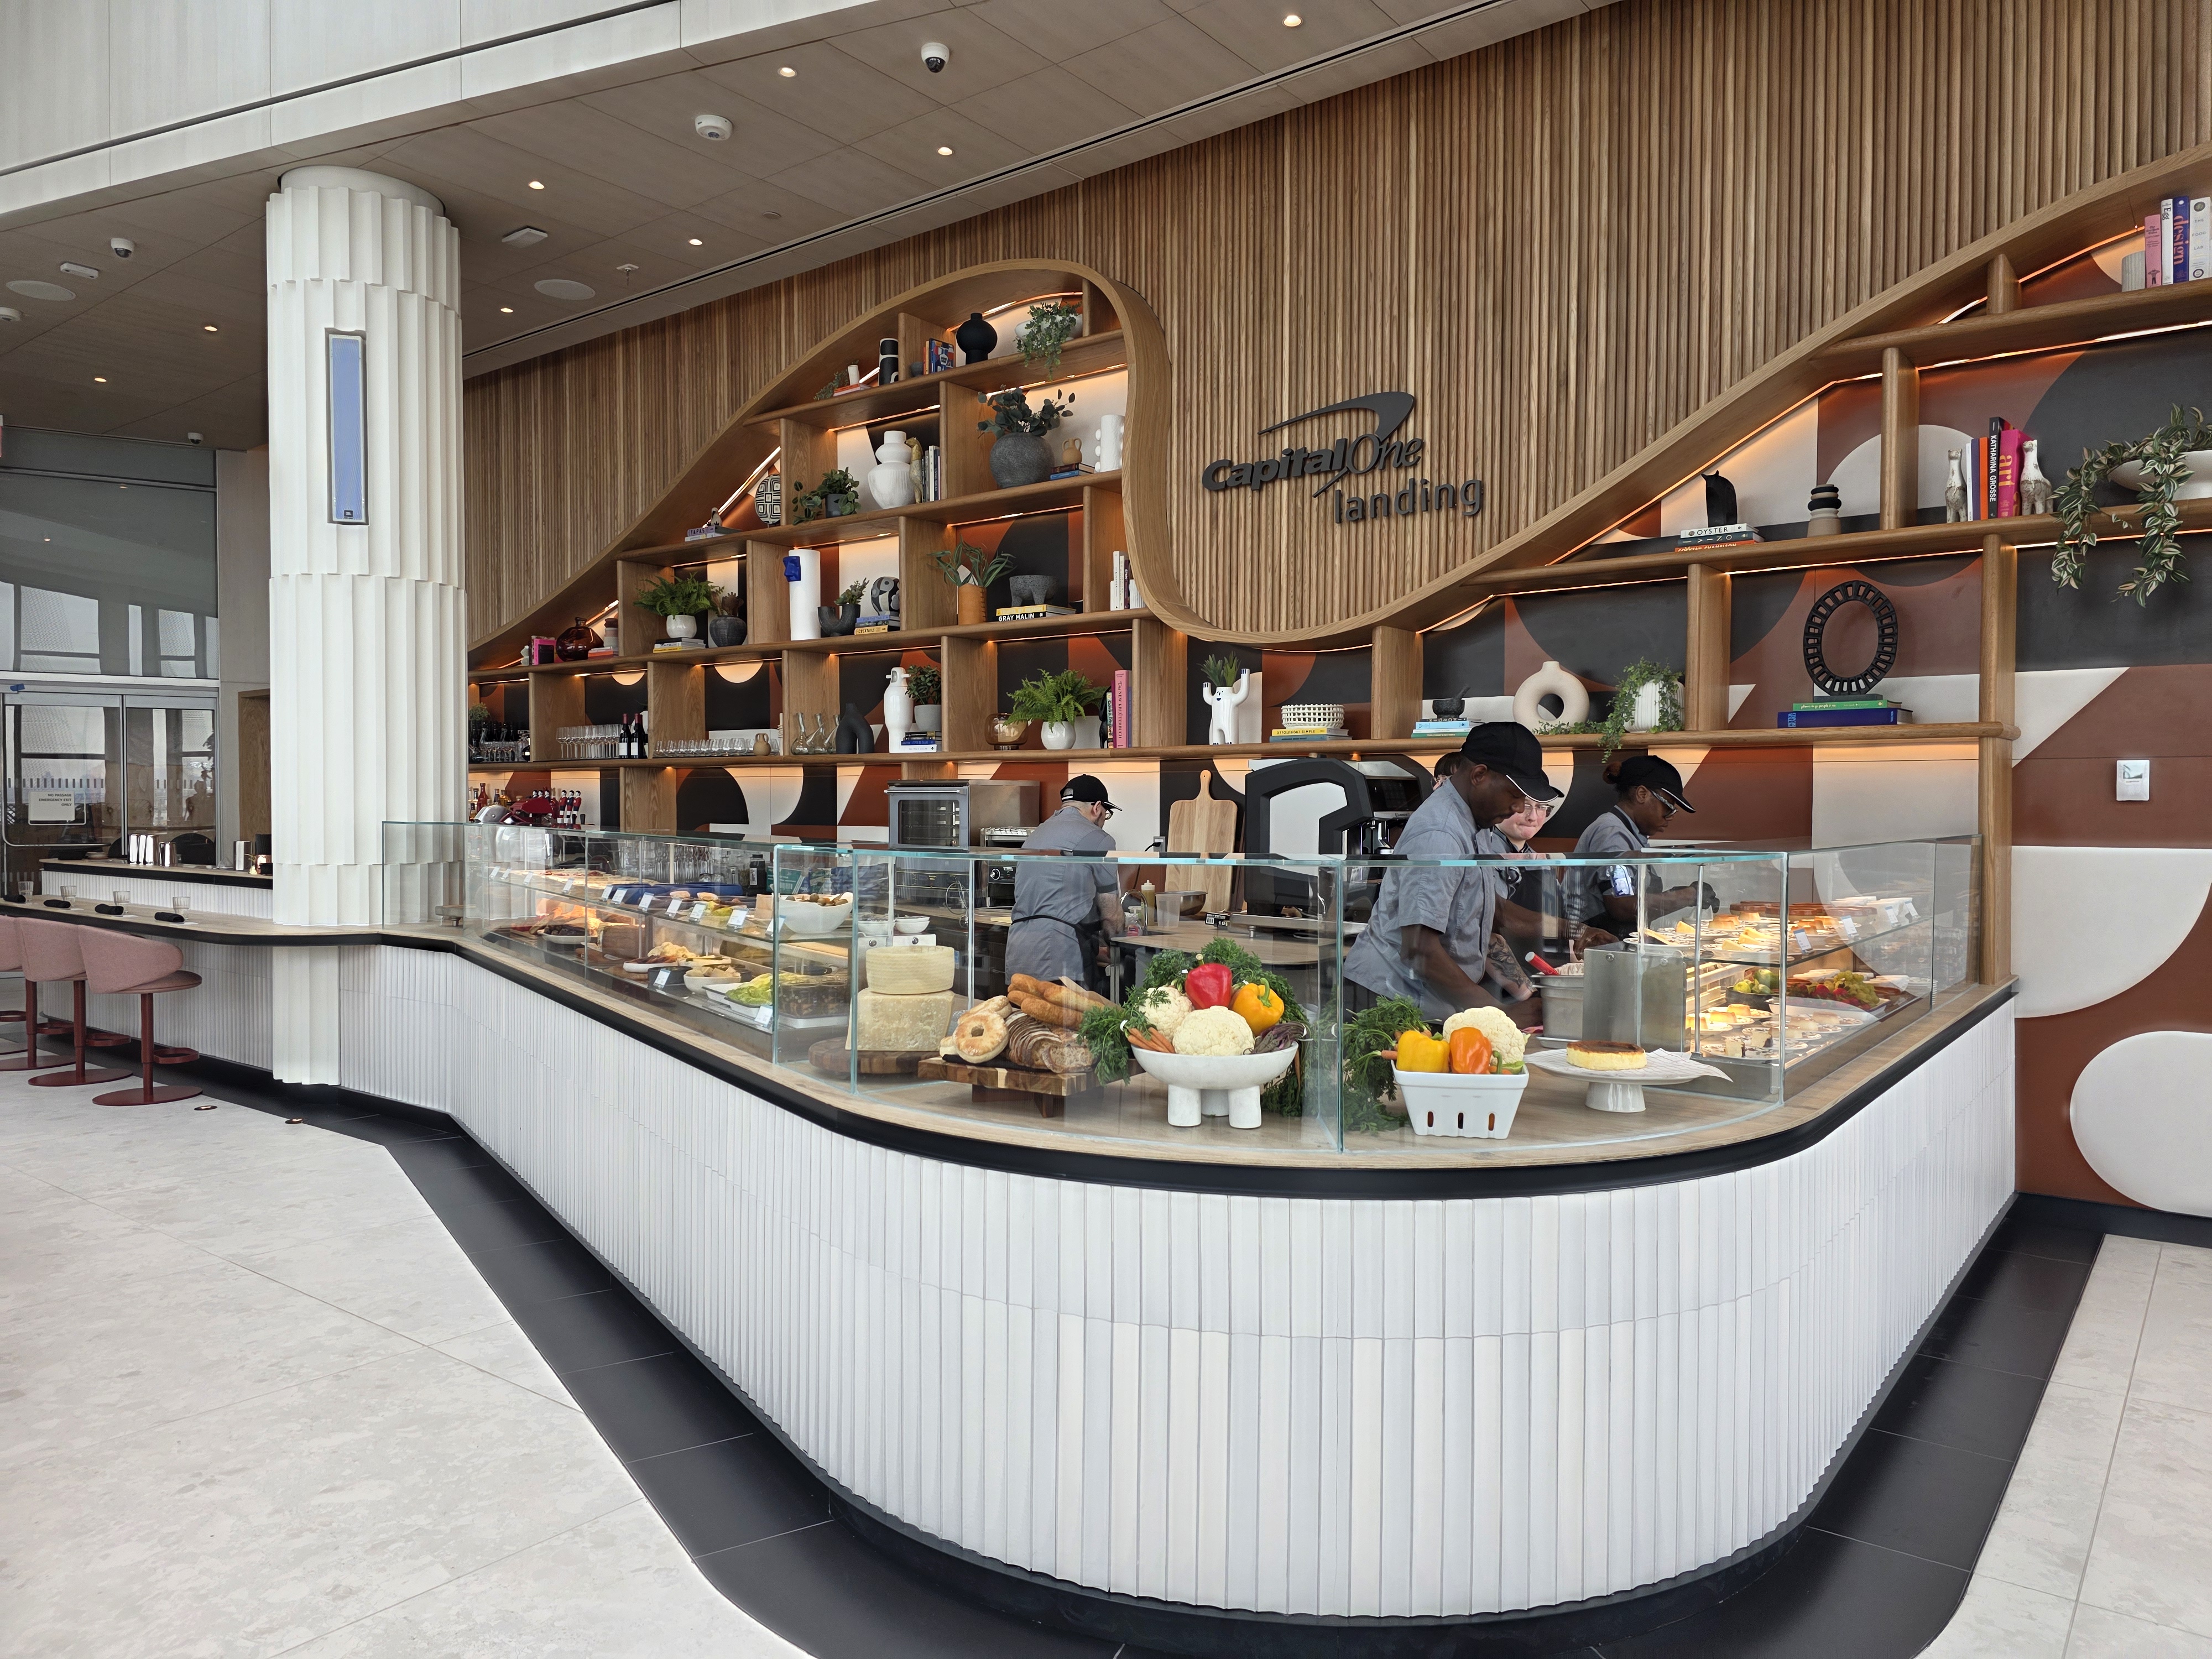
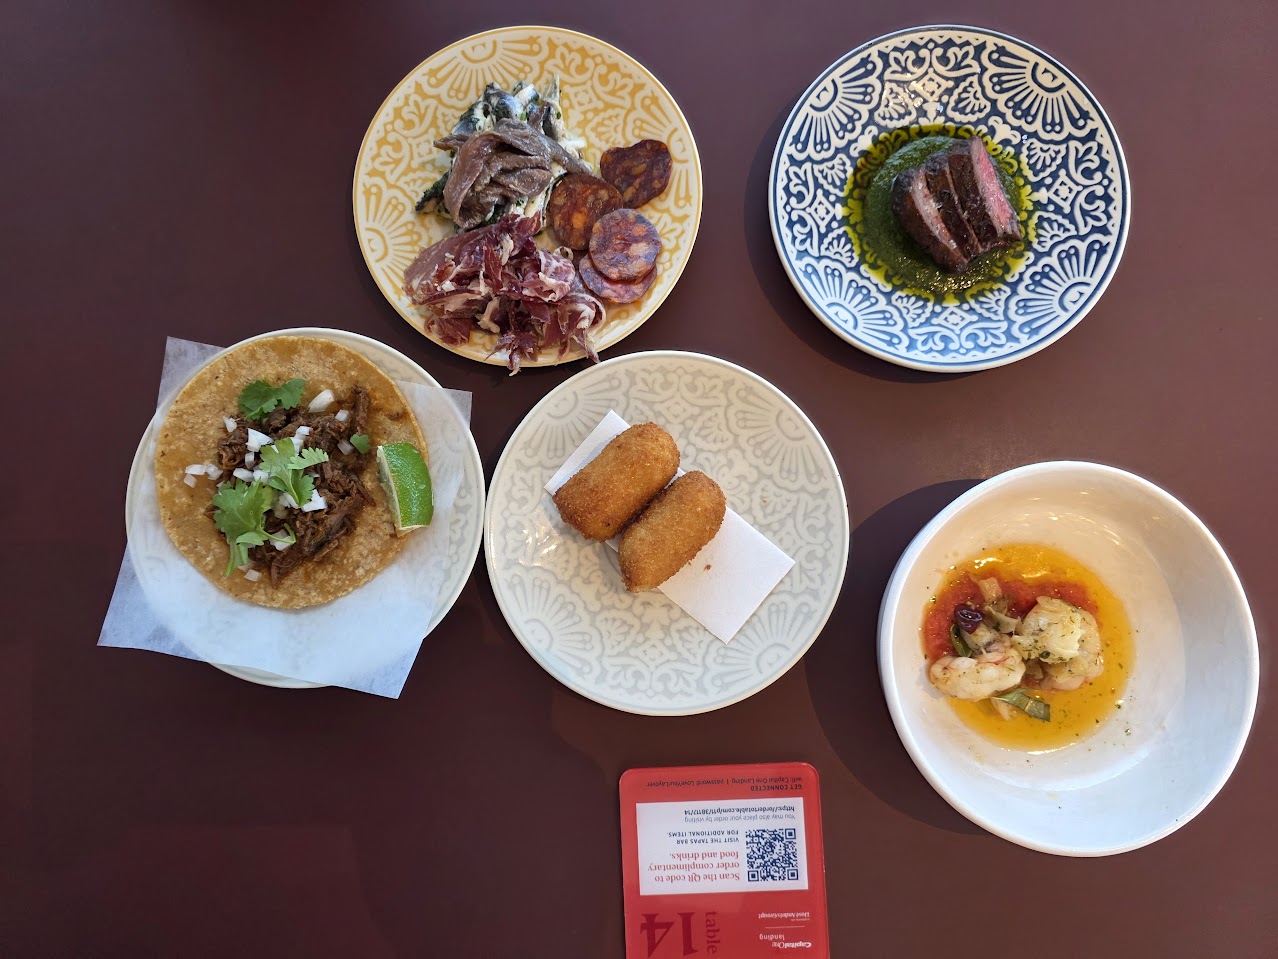
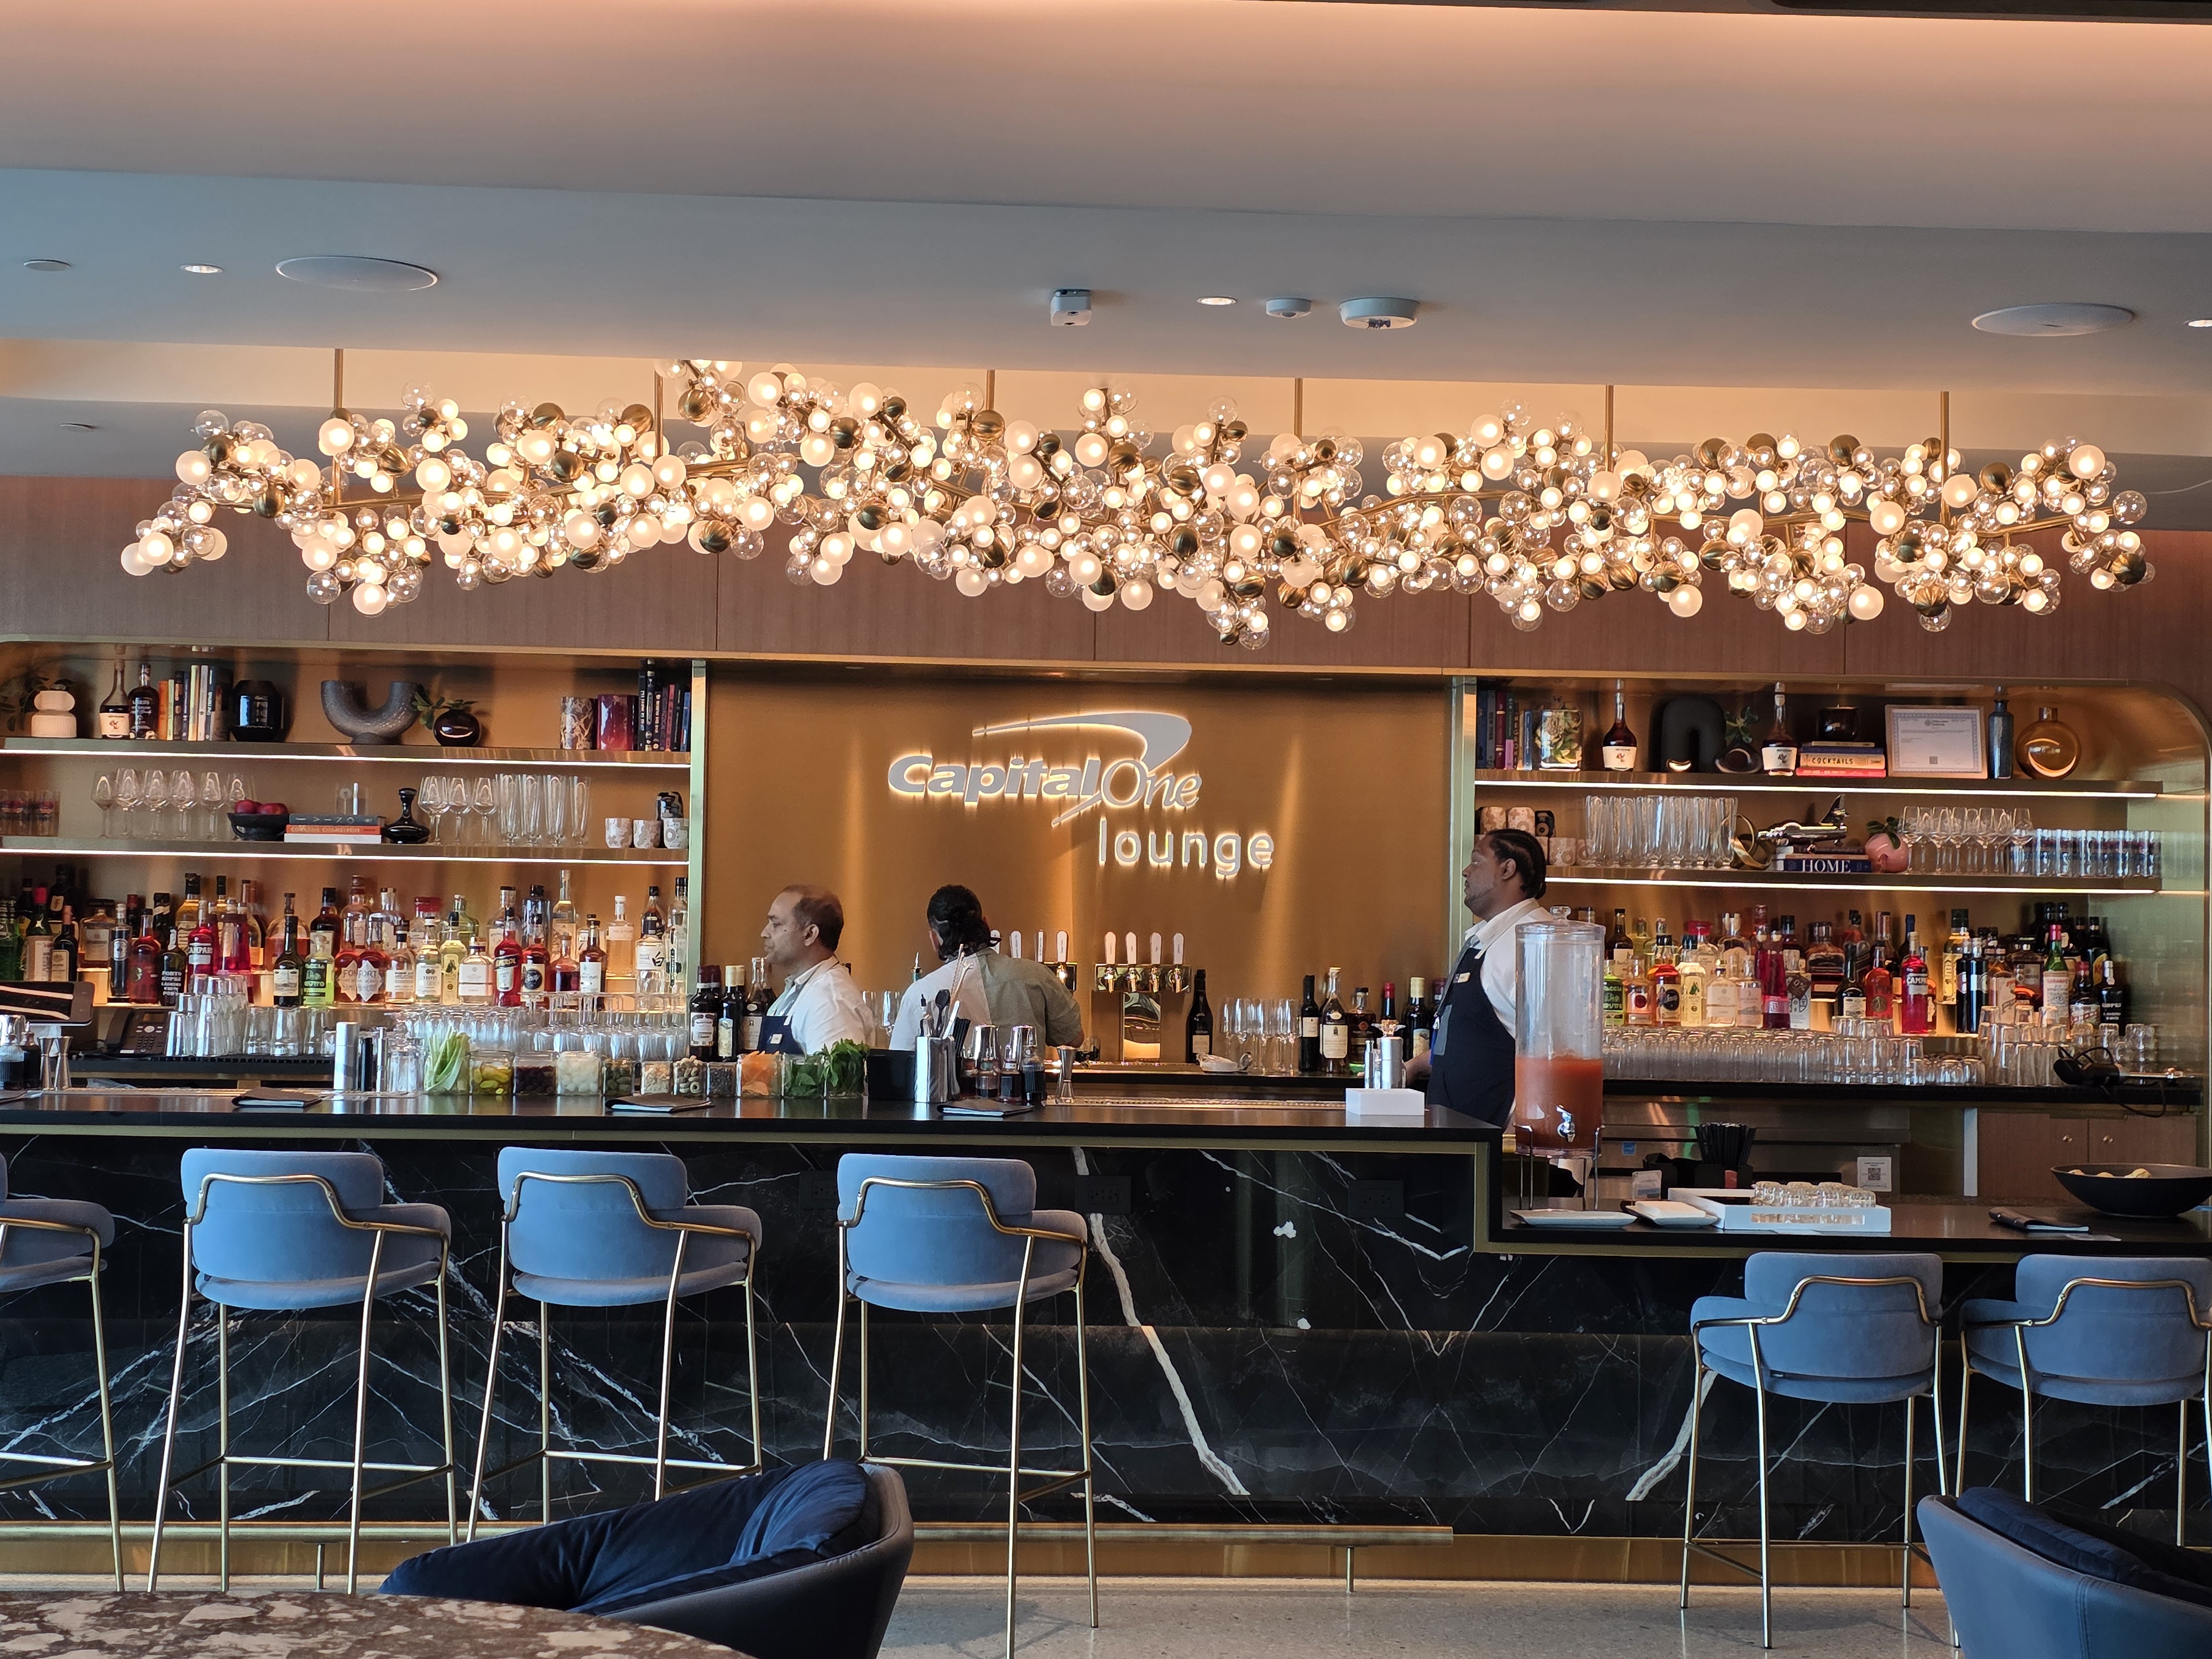
Capital One has similarly redefined the expectation for airport amenities with its "Landing" concepts at airports such as Washington National (DCA) and New York LaGuardia. By prioritizing high-quality, regionally inspired food and beverage programs, Capital One has successfully differentiated its product from traditional bank-operated lounges.
Strategic Allocation of Spending: A Case Study in Optimization
To achieve maximum utility, a cardholder must identify which instruments perform best in specific merchant categories.
- Travel and Hospitality: The Chase Sapphire Reserve remains a dominant force for travel-related expenditures. Its ability to earn 8x points on purchases through Chase Travel and 4x points on direct travel bookings makes it a cornerstone for those with significant business or leisure travel volume. Furthermore, the integration of "The Edit" allows users to earn hotel loyalty points and elite status credits while leveraging annual statement credits, effectively lowering the net cost of the card.
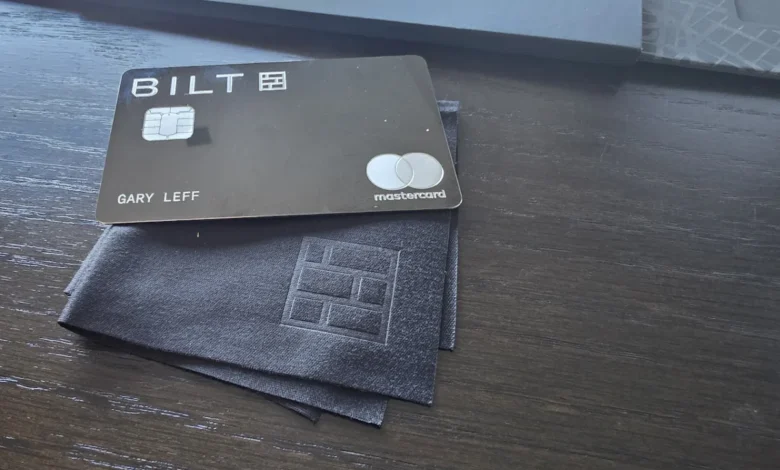
- Everyday "Catch-All" Spending: Products such as the Bilt Palladium Card have emerged as primary tools for non-category-specific spending. By offering competitive points-per-dollar ratios and the ability to earn points on rent and mortgage payments, these cards address a historical gap in the rewards market. The potential to earn 2 to 3 points per dollar on everyday transactions, combined with access to premium transfer partners, positions this as a high-value asset for the average consumer.
- Niche Category Accelerators: The American Express Gold Card has cemented its place as a essential tool for food-related expenses, specifically groceries and dining. With a focus on high-volume, recurring household expenditures, the card’s earning structure is designed to offset its annual fee through a combination of category multipliers and targeted credits. Similarly, the Citi Strata Elite card offers strategic utility for weekend dining, capitalizing on specific time-based high-multiplier windows to maximize point accumulation.
Balancing Annual Fees and Statement Credits
A critical component of modern credit card management is the "break-even" analysis. Premium cards often carry annual fees ranging from $395 to $895. These fees are rarely intended to be paid without a corresponding offset.
For instance, the Capital One Venture X rewards card features a $395 annual fee that is largely mitigated by a $300 annual travel credit and an annual bonus of 10,000 miles. This structure essentially turns the card into a low-cost or net-positive instrument for the frequent traveler. The American Express Platinum card, despite its high annual fee, offers a vast array of statement credits—covering everything from airline incidentals to digital entertainment—that, when fully utilized, can result in a net cost far below the headline fee.
Chronology of Benefit Realization
The lifecycle of a high-end credit card follows a predictable, yet essential, timeline for the consumer:
- Months 0–3 (Acquisition Phase): The focus is on meeting the minimum spend requirements to trigger substantial welcome bonuses. This period often involves consolidating spending onto a single card to ensure the bonus threshold is met before the deadline.
- Months 4–12 (Utilization Phase): The card is integrated into the user’s long-term spending strategy based on its specific multipliers (e.g., dining, travel, or groceries).
- Annual Anniversary: This is the pivotal moment for evaluation. The cardholder must assess whether the card’s annual benefits—such as anniversary bonus points or recurring travel credits—justify the renewal of the annual fee. If the value proposition has diminished, the consumer may choose to downgrade to a no-fee version of the card or cancel the account.
Broader Implications and Market Trends
The aggressive competition among credit card issuers has led to a "golden age" for consumers, provided they remain disciplined. The primary risk for the average cardholder is "feature creep," where the pursuit of complex, high-fee cards leads to inefficient spending.
Financial analysts note that the rise of "authorized user" strategies—whereby families share access to high-earning cards—has become a standard practice for maximizing household rewards. However, this requires significant administrative oversight. The complexity of tracking multiple expiration dates, bonus categories, and credit cycles necessitates a systematic, almost professional approach to personal finance.

Moreover, the shift toward transfer-partner-based rewards programs has made the "point" more volatile and potentially more valuable. Unlike simple cash-back programs, where the value is fixed, transfer partners allow for outsized value when points are redeemed for premium cabin international travel or luxury hotel suites. This shift rewards the informed consumer who takes the time to research partner charts and booking availability.
Conclusion
Effective credit card management is less about owning a specific brand and more about maintaining a fluid, data-driven strategy. By understanding the core purpose of each card—whether it be for lounge access, high-multiplier category spending, or long-term point accumulation—consumers can leverage these financial tools to subsidize significant portions of their travel and lifestyle costs. As issuers continue to introduce new credits and benefits, the most successful cardholders will remain those who treat their portfolios as a dynamic, evolving asset class rather than a static collection of plastic.
Related posts: